Life Insurance Medical Exam: What to Expect Step by Step
A life insurance medical exam takes 20 to 40 minutes and can lower your premiums. Call 8332124240 to compare quotes and prepare with confidence.
By Axion Vale
You have finally decided to protect your family with a life insurance policy, and then the application asks whether you consent to a medical exam. For many applicants, that single question triggers more anxiety than any other part of the process. The good news is that a life insurance medical exam is a short, routine appointment, usually lasting 20 to 40 minutes, and it often works in your favor. A clean exam can unlock significantly lower premiums, sometimes saving you hundreds of dollars per year compared to a no-exam policy. Understanding exactly what happens, who pays for it, and how to prepare removes the guesswork and helps you present your health in the best possible light.
Why Insurers Ask for a Medical Exam
Life insurance is priced on risk. When a carrier agrees to pay a death benefit, it wants reasonable confidence that the policyholder will live a normal lifespan. A medical exam gives underwriters objective data about your height, weight, blood pressure, cholesterol, blood sugar, and other health markers. That data is combined with your application answers, prescription history, and motor vehicle records to build a complete risk profile.
This might sound intrusive, but it is actually good news for healthy applicants. Because the insurer verifies your health directly, it does not have to assume the worst. People who pass a fully underwritten exam frequently qualify for the best rate classes, which can cut premium costs dramatically over a 20 or 30 year term. If you would rather avoid the exam entirely, that option exists too, but simplified issue policies usually carry higher rates to offset the insurer's added uncertainty.
It also helps to know who is paying. In the vast majority of cases, the insurance company covers the cost of the exam, and it is typically conducted free of charge to you. A paramedical professional, often a nurse or phlebotomist contracted by the carrier, comes to your home or office at a time you choose. You are not expected to schedule a clinic visit or pay a copay.
How to Prepare Before Exam Day
Preparation matters more than most people realize. Certain habits in the 24 hours before your appointment can temporarily distort your results, and distorted results can push you into a higher rate class or trigger a request for a second exam. You do not need to do anything extreme. Simply follow a sensible routine.
Here are the key steps to take in the days leading up to your appointment:
- Fast for 8 to 12 hours before the exam if the insurer requests it, since cholesterol and glucose readings are affected by recent meals. Water and prescribed medications are usually fine.
- Avoid alcohol for at least 24 hours, because it can elevate liver enzymes and blood pressure readings.
- Skip strenuous exercise the day before, since intense workouts can temporarily raise protein and enzyme levels in your blood.
- Get a full night of sleep and limit caffeine on exam morning, as both affect blood pressure and heart rate.
- Gather a list of your current medications, dosages, and the names of any doctors you have seen recently.
One practical tip that many applicants overlook: schedule the exam for early morning if possible. You will already be fasting overnight, you will be well rested, and your stress level tends to be lower before the day's demands pile up. If you take blood pressure medication, ask the examiner or your agent whether you should take it as usual, since skipping it could produce a misleadingly high reading.
If affordability is a concern while you prepare, it helps to understand how carriers weigh exam results against pricing, which is exactly what guides like our breakdown of affordable life insurance plans that cut costs are designed to clarify. The healthier your verified profile, the more negotiating room you have on premium.
What Actually Happens During the Exam
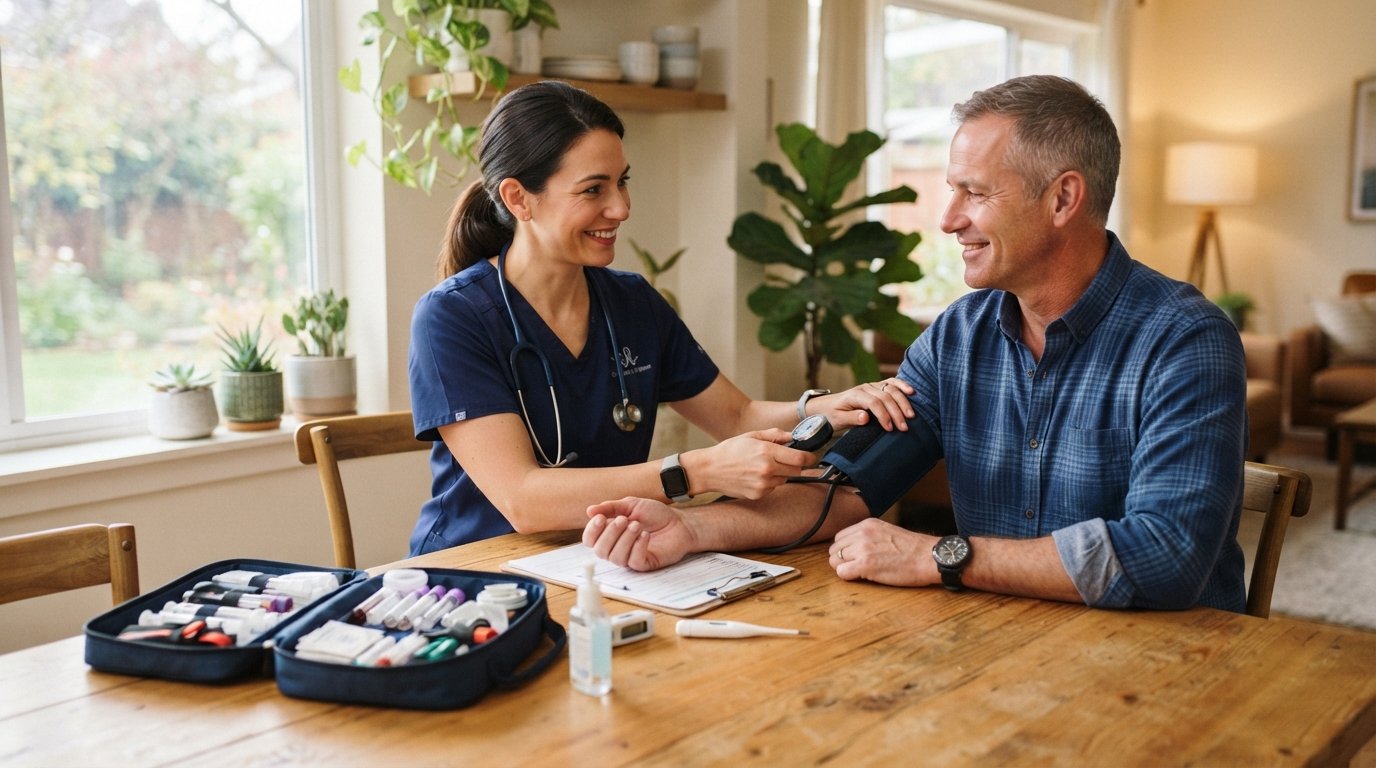
The exam itself is straightforward and non-invasive apart from a single blood draw. A licensed paramedical examiner arrives at your home, workplace, or another agreed location with a small medical kit. After confirming your identity, the examiner walks through a series of simple measurements and questions.
You can expect the following sequence:
- Verification of your identity and a review of the consent forms you signed with your application.
- Measurement of height, weight, pulse, and blood pressure, sometimes taken more than once for accuracy.
- Collection of blood and urine samples, usually from a vein in your arm, which takes only a minute or two.
- A brief health questionnaire covering your medical history, medications, tobacco or nicotine use, and any recent treatments.
- Optional additional tests, such as an electrocardiogram (EKG) or oral fluid swab, depending on your age, coverage amount, and the carrier's requirements.
After the visit, the examiner sends your samples to a certified laboratory and forwards the results to the insurance company's underwriting department. You typically will not receive the results directly unless you request them, though many carriers now share them through a secure portal. From there, an underwriter reviews everything alongside your application and issues a final offer, often within one to three weeks, though some carriers move faster.
What the Exam Typically Includes
Not every applicant receives the same test panel. Requirements scale with your age and the size of the policy you are requesting. A healthy 30 year old applying for a modest term policy might only need basic vitals and a blood draw, while a 55 year old applying for a larger policy may face a more comprehensive workup.
Common components include blood pressure and pulse readings, height and weight to calculate body mass index, blood tests for cholesterol, glucose, liver and kidney function, and markers associated with HIV or hepatitis, a urinalysis to screen for kidney issues and nicotine, and a questionnaire about your medical and lifestyle history. For larger policies, carriers sometimes add an EKG to check heart rhythm or a cognitive screening for older applicants. If you use tobacco or nicotine in any form, expect a specific test for cotinine, a byproduct that stays detectable for several days.
Understanding this checklist in advance helps you avoid surprises. If you know a particular value, such as blood pressure or cholesterol, has been borderline in the past, mention it to your agent before the exam so they can note it in the application and potentially shop your case to carriers with more forgiving underwriting guidelines.
How Results Affect Your Premium and Options
Your exam results feed directly into the rate class the insurer assigns you. Preferred plus is the best tier, reserved for applicants with excellent health markers and no significant history. Preferred, standard plus, and standard follow in descending order, and each step down means a higher monthly premium. Table ratings apply to applicants with more serious health concerns and can raise costs substantially.
The encouraging reality is that most applicants land in a reasonable rate class. Slightly elevated cholesterol or well-controlled blood pressure does not automatically disqualify you, and many carriers will still offer competitive pricing. If your results come back worse than expected, you generally have options: accept the offer, ask your agent to request reconsideration with additional medical evidence, or apply with a different carrier whose underwriting philosophy fits your profile better.
For applicants who truly want to skip the exam, simplified issue and final expense policies rely on health questionnaires instead of labs. These can be a good fit for older applicants or those with complex health histories, but the trade-off is higher premiums per thousand dollars of coverage. It is worth comparing both paths before committing.
Special Situations: Age, Health Conditions, and No-Exam Alternatives
Age plays a major role in what the exam looks like. Applicants under 40 often receive a streamlined panel, while applicants over 60 may be asked for an EKG, additional blood markers, or a cognitive assessment. None of these tests are painful, and the examiner is trained to keep the process comfortable.
If you live with a chronic condition such as diabetes, high blood pressure, or a previous cardiac event, do not assume you will be declined. Carriers price for these risks every day, and some specialize in them. What matters most is control: stable A1C readings, consistent medication use, and documented follow-up care all work in your favor. Being honest on the application is essential, since the exam will reveal anything you leave out, and nondisclosure can lead to a rescinded policy years later when your family needs it most.
For anyone weighing coverage options more broadly, including health coverage alongside life protection, resources such as NewHealthInsurance.com can help you compare plans and understand how different types of coverage fit together. Coordinating your life and health insurance decisions often reveals savings that neither policy shows on its own.
After the Exam: Timelines and Next Steps
Once the examiner leaves, the clock starts on underwriting. Samples go to a lab, results are returned to the carrier, and an underwriter assembles the full picture. In most cases you will hear back within two to four weeks, though accelerated programs can deliver a decision in days. If the carrier needs clarification, such as a note from your physician about a past diagnosis, the process can stretch a little longer.
When your offer arrives, review it carefully. Check the rate class, the death benefit, the term length, and any exclusions. If the offer is better than expected, you can lock it in. If it is worse, ask your agent whether a different carrier or a revised coverage amount might produce a better outcome. You are never obligated to accept a policy you did not ask for, and comparing multiple offers remains the single most reliable way to find the lowest rate.
A life insurance medical exam is not a hurdle to fear. It is a short appointment that gives you leverage: proof of good health in exchange for lower premiums and long-term peace of mind for the people who depend on you.