Life Insurance for Stay at Home Parents Who Have No Income
Life insurance for stay at home parents who have no income protects your family's stability. Call (833)-212-4240 to compare affordable term quotes and secure coverage today.
By Tarian Vex
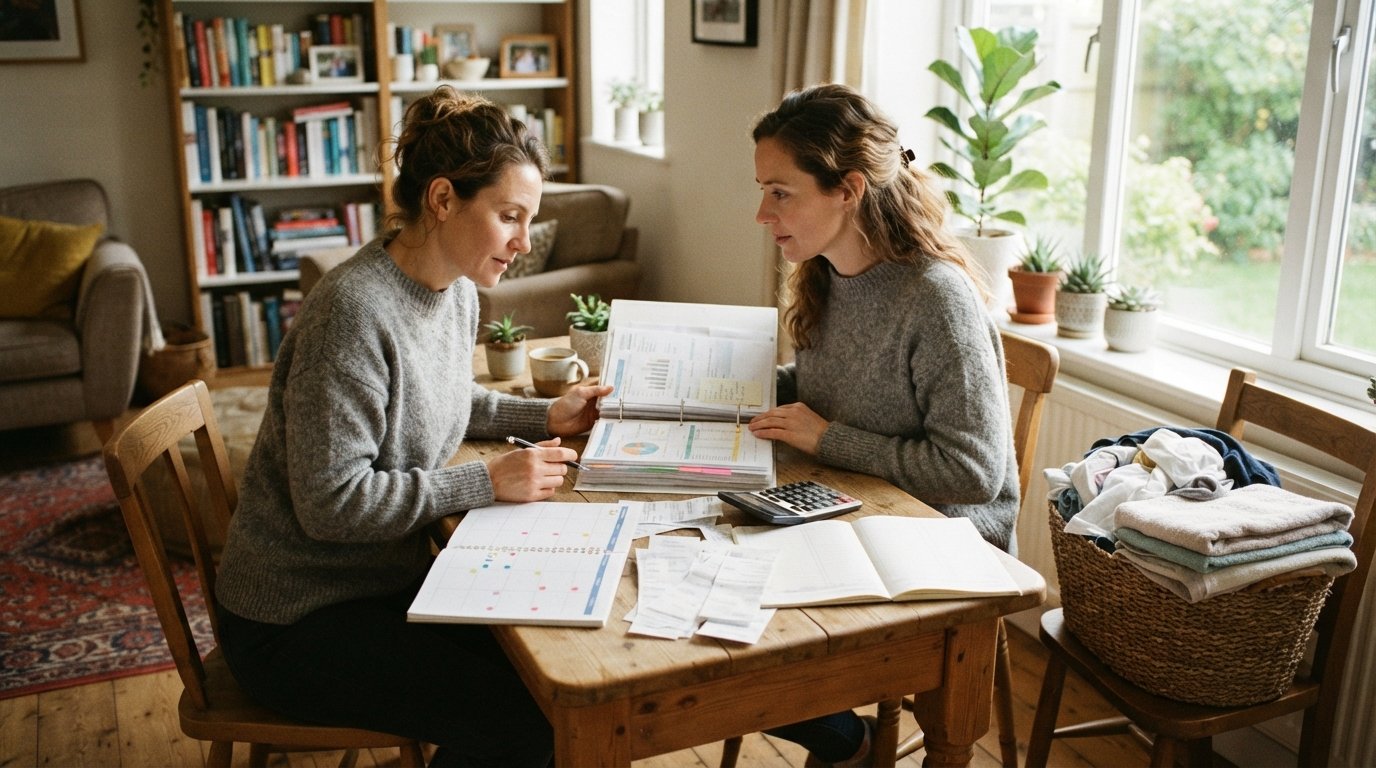
When you are a stay at home parent, your days are filled with school runs, meal preparation, booger wiping, and an endless game of pickup. There is no paycheck attached to this work, but its value is immense. If something were to happen to you, your family would not just grieve emotionally; they would face a financial earthquake. The cost of replacing your unpaid labor, from childcare to household management, can be staggering. That is why life insurance for stay at home parents who have no income is not just a nice idea: it is a critical piece of financial security. Insurers do not care that you do not earn a salary. They care about the financial risk your absence would create. In this guide, we will walk through exactly how to value your contributions, size a policy, and find affordable coverage on a single income.
The Hidden Economic Value of Unpaid Work
Many stay at home parents feel guilty or confused about applying for life insurance because they do not bring home a paycheck. But the work you do has a direct market replacement cost. If you were suddenly gone, your family would need to pay someone else to do at least some of what you do for free. That is the foundation of how insurers view your insurable value. They are not looking at your salary; they are looking at the financial burden your family would face if they lost you. This is why life insurance for stay at home parents who have no income is not only possible but often essential.
Consider the three main categories of your daily labor: childcare, household management, and transportation. Each has a clear market rate. Full time childcare in the United States can easily cost $10,000 to $30,000 per year per child, depending on where you live. Household management includes cleaning, laundry, cooking, budgeting, and scheduling appointments. Transportation includes driving kids to school, activities, and medical visits. When you add these up, the annual replacement cost for a stay at home parent often lands between $40,000 and $80,000. That is the equivalent of a full time job. Insurers recognize this value, and many now have specific underwriting guidelines that allow non-earning parents to qualify for substantial coverage.
If you are unsure whether you qualify, it helps to work with a professional who understands these nuances. You can find the best life insurance brokers near me today and ask them specifically about insurable interest for non-earning parents. They will help you document your role and present your case to carriers. The key is to shift the conversation from income replacement to service replacement. Once you frame your work in economic terms, the need for coverage becomes obvious.
How to Size Coverage Without a Salary to Multiply
The traditional rule of thumb for life insurance is to multiply your income by 10 to 15 times. But when you have no income, that formula does not work. Instead, you need to use a replacement cost approach. Start by estimating what it would cost your family to hire out your core responsibilities. The most common method is to add up the annual cost of childcare, housekeeping, and transportation. Then multiply that number by the number of years your children will still need care. For example, if you have a 5 year old and a 2 year old, you might need coverage for the next 16 to 18 years. If replacement costs are $50,000 per year, that is $800,000 to $900,000 in coverage. That may sound high, but it reflects the reality of raising children.
However, you do not need to cover everything. Many families take a more moderate approach. They calculate the cost of childcare only for the years until the youngest child enters school, and then a smaller amount for after school care and household help. Another approach is to cover a specific goal, such as funding a college savings plan or paying off the mortgage. The right amount depends on your family's budget and your partner's ability to absorb some of the household duties. A good rule is to aim for at least $250,000 to $500,000 in term coverage, which is often affordable for a single income family.
To make this concrete, consider a family with two children, ages 3 and 6. The stay at home parent provides full time care. If they passed away, the surviving spouse would need to pay for daycare for the 3 year old (about $12,000 per year) and after school care for the 6 year old (about $6,000 per year) for the next 12 years. They might also need a house cleaner ($4,000 per year) and someone to handle transportation ($3,000 per year). Total annual cost is $25,000. Over 12 years, that is $300,000. Adding a buffer for inflation and unexpected costs, a $400,000 term policy would be reasonable. That amount is often available for a healthy 30 year old at a very low premium.
Affordable Term Options on a Single Income Budget
One of the biggest fears for single income families is that life insurance will be too expensive. The good news is that term life insurance is incredibly affordable, especially for younger parents. Term life provides coverage for a set number of years, typically 10, 20, or 30 years. It has no cash value, which keeps premiums low. For a healthy 30 year old woman, a $500,000 20 year term policy might cost $20 to $30 per month. That is less than a streaming subscription. For a 35 year old man, a $500,000 policy might be $25 to $40 per month. These rates are for standard health, and they can be even lower for preferred plus. The key is to shop around and compare quotes from multiple carriers.
If you are a stay at home parent with no income, some insurers may require a bit more paperwork. They may ask for a statement from your partner confirming your role in the household, or they may simply accept your spouse's income as the basis for financial underwriting. Many carriers now have streamlined processes for non-earning parents, including simplified issue policies that do not require a medical exam. These policies are more expensive per dollar of coverage, but they are faster and easier to obtain. For a healthy parent, fully underwritten term is usually the best value. You can get personalized quotes by using a comparison platform. For example, USLifeQuote helps you compare offers from multiple carriers in one place, ensuring you find the lowest rate for your family's needs.
Budgeting for premiums on a single income requires some creativity. Many families find that they can redirect a small amount from discretionary spending, such as eating out or subscription services, to cover a term policy. Others choose a slightly smaller coverage amount to keep the premium within their comfort zone. The important thing is to get some coverage in place rather than waiting for the perfect policy. Even a $250,000 term policy can provide significant relief for a surviving spouse, covering childcare and household help for several years.
Coordinating Coverage With Your Partner
Life insurance is not just for the stay at home parent. Both partners need coverage, but the amounts and types may differ. The working partner's coverage should replace their income and cover ongoing expenses like the mortgage, debts, and future education costs. The stay at home parent's coverage should replace the value of their unpaid services. When you coordinate both policies, you create a complete safety net for your children. A common mistake is for the working partner to be overinsured while the stay at home parent has nothing. That leaves a gap: if the stay at home parent dies, the working partner may have to cut back on work or pay for expensive childcare, which can strain the family's finances.
To align your coverage, sit down with your partner and list all the tasks each of you handles. Then estimate the cost to replace those tasks if one of you were gone. You may find that the stay at home parent needs just as much coverage as the working parent, especially when children are young. You should also consider the duration of the policies. A 20 year term policy might cover you until your youngest child is out of high school. A 30 year term policy might cover you until your mortgage is paid off. Choose terms that match your family's timeline. Finally, review your coverage every few years or after major life events, such as a new baby, a move, or a change in income.
When you apply, be honest about your role. If you are a stay at home parent, tell the agent that you provide full time care for your children. This helps the insurer understand your insurable interest. Some carriers may ask for a letter from your spouse or a copy of your household budget. These are normal requests. By working with an experienced agent, you can navigate the underwriting process smoothly. Remember, the goal is to protect your family's standard of living, no matter which parent is providing the care.
Overcoming Common Objections and Next Steps
Many stay at home parents hesitate to apply for life insurance because they think they will be rejected. It is true that some insurers are more conservative, but the market has evolved. Many top rated carriers now actively seek to insure non-earning parents because they understand the financial risk. If you have health issues, you may still qualify for coverage through simplified issue or guaranteed issue policies. These options have higher premiums, but they provide peace of mind. The worst thing you can do is assume you are not eligible without checking. A quick phone call or online quote request can clarify your options.
Another common objection is cost. But when you compare the monthly premium to the cost of childcare or a house cleaner, the value is clear. For the price of a few cups of coffee per week, you can ensure that your family can afford to maintain their lifestyle if the unthinkable happens. Think of it as an investment in your family's stability. To get started, gather some basic information: your age, health history, and the amount of coverage you are considering. Then use a quote comparison tool to see real numbers. You can also speak with a licensed agent who can walk you through the process and answer your questions.
Finally, do not let the lack of a paycheck stop you from protecting your family. Your work as a stay at home parent has enormous value, and life insurance is the tool that recognizes that value in financial terms. By valuing your unpaid work, sizing coverage based on replacement costs, choosing affordable term options, and coordinating with your partner, you can secure the protection your family deserves. Take the first step today by requesting a quote and exploring your options. Your family's future is worth it.