Life Insurance for Parents with a Mortgage and Student Loans
Life insurance for parents with a mortgage and student loans protects your family and co-signers. Call (833)-212-4240 to compare term quotes and close coverage gaps.
By Tarian Vex
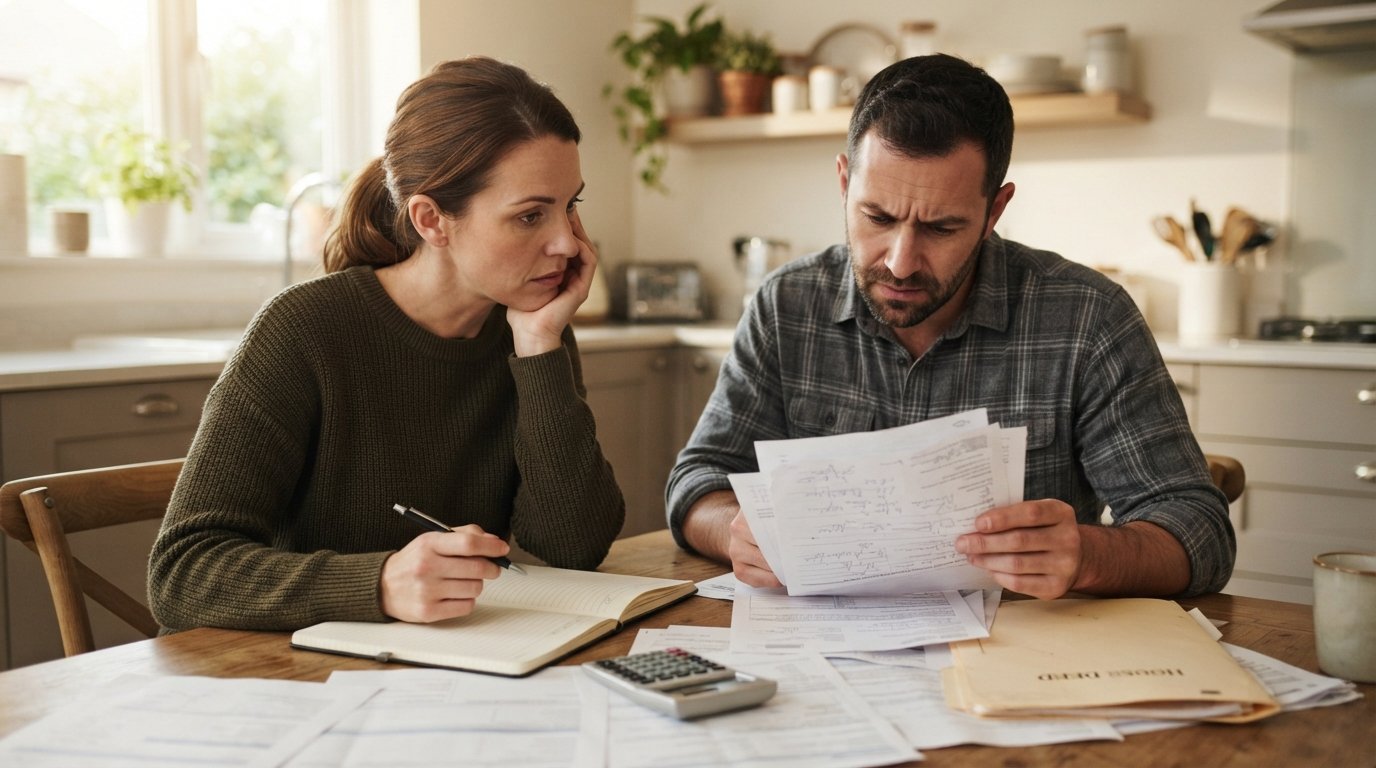
You have a mortgage, student loans, and children who depend on you. The math is simple: if something happens to you, the people you love inherit the bills. Life insurance for parents with a mortgage and student loans is not just another monthly expense; it is the financial firewall that keeps your family in their home and your student debt from following your co-signer. Without a plan, your mortgage can go into default and your student loans can land on a parent or spouse who co-signed. This guide shows you how to size coverage correctly, align term lengths to your payoff schedule, and avoid the gaps that mortgage protection policies often leave behind.
Why Mortgage and Student Debt Change Your Coverage Math
Most life insurance calculators start with income replacement: multiply your salary by 10 or 15, then subtract existing savings. That formula ignores the two largest debts many parents carry. A mortgage is a secured debt tied to the roof over your family's head. Student loans are unsecured but often co-signed, which means a survivor or a parent can become legally responsible after your death. Both obligations must be added to your coverage calculation, not treated as background noise.
Consider a parent earning $75,000 with a $300,000 mortgage and $40,000 in student loans. A simple income replacement rule might suggest $750,000 in coverage. But that figure assumes the mortgage and student loans are separate from income replacement. In reality, your family needs enough to pay off the mortgage (or keep paying it), retire the student debt, and replace your income for the years your children still depend on you. Adding the debts to the income replacement number prevents a shortfall that could force a sale of the home.
Life insurance for parents with a mortgage and student loans should be built from three layers: income replacement for daily living, debt elimination for the mortgage and student loans, and a buffer for final expenses and unexpected costs. When you request quotes through LifeAgency, you can compare term policies that cover all three layers without overpaying for extras you do not need.
How to Calculate Coverage That Includes Both Debts
Start with a debt inventory. List the remaining balance on your mortgage, the total of all student loans (including private and federal), and any other debts that would survive you, such as auto loans or credit cards. Then calculate income replacement: multiply your annual income by the number of years your children will still be minors or in college. Add the two figures together, then subtract savings and existing coverage. The result is your target death benefit.
Here is a simple framework you can apply in a few minutes:
- Add your mortgage balance and student loan totals. For example, $300,000 mortgage plus $40,000 student loans equals $340,000 in debt that must be cleared.
- Multiply your annual income by the years of dependency. If you earn $75,000 and your youngest child is 10, you might use 10 years of income replacement, or $750,000.
- Add a buffer for final expenses and emergency costs, typically $15,000 to $30,000.
- Subtract existing savings, investments, and any group life insurance from your employer.
Using the example above, $340,000 in debt plus $750,000 in income replacement plus a $20,000 buffer equals $1,110,000. Subtract $100,000 in savings and group coverage, and your target coverage is roughly $1,010,000. That number may sound high, but term life insurance for a healthy 35-year-old parent is often surprisingly affordable compared to the cost of a foreclosure or a co-signer being pursued for student loans.
Do not forget to account for the interest that would accrue on student loans if they are not paid off immediately. Federal student loans may be discharged upon death, but private loans often are not. If your loans are private and co-signed, the co-signer may be required to continue payments. Adding the full balance to your coverage ensures the debt can be retired outright.
Why Mortgage Protection Insurance Alone May Leave Gaps
Mortgage protection insurance is often marketed to new homeowners as a simple way to cover the mortgage. It typically pays a benefit that decreases as the mortgage balance declines, and it is tied to the lender. While it can be useful, it is not a substitute for a comprehensive term policy. Mortgage protection usually covers only the mortgage, leaving your student loans, income replacement, and final expenses unprotected. It also may pay the lender directly rather than your family, limiting how the money can be used.
Another gap: mortgage protection policies often have a declining death benefit that matches the amortization schedule. If you sell the home or refinance, the policy may not follow your new situation. A level term policy, by contrast, pays a fixed death benefit to your beneficiaries, who can use it to pay off the mortgage, cover student loans, or replace income as they see fit. For parents with both a mortgage and student loans, a level term policy provides flexibility that a lender-specific product cannot match.
If you already have mortgage protection insurance, review it alongside your student loan balances. You may find that the coverage is too narrow. A licensed agent can help you compare term quotes that cover all your debts and replace the mortgage protection policy if it is not serving your family's full needs.
Aligning Term Length with Your Payoff Schedule
Term life insurance is the most cost-effective way to cover debts that have a defined payoff date. A 30-year mortgage calls for a term that lasts at least 30 years, unless you plan to sell or refinance sooner. Student loans typically have 10- to 20-year repayment timelines. The goal is to match the term length to the debt with the longest remaining schedule, then consider a separate policy for shorter debts if needed.
For example, if your mortgage has 27 years left and your student loans have 12 years left, a 30-year term policy covers both debts for their full duration. You might also consider a 15-year term policy for the student loans if the premium difference is significant, but a single 30-year policy is often simpler and may be more affordable than stacking multiple policies. Work with an agent to compare the cost of one long term versus two shorter terms.
Keep in mind that term life insurance for parents with a mortgage and student loans should also account for the years your children are dependent. If your youngest child is 5, you need coverage for at least 18 to 22 years, which aligns well with a 20- or 30-year term. Choosing a term that ends before your children are independent could leave them unprotected during the years they need you most.
Co-Signed Loans: What Happens to the Co-Signer After a Death
Student loans are often co-signed by a parent or spouse. If you die, the co-signer may become responsible for the remaining balance, depending on the lender and the loan terms. Federal student loans are generally discharged if the borrower dies, but private loans may not be. Even federal loans can require documentation and may have tax implications. For private loans, the co-signer is typically on the hook unless the lender offers a death discharge benefit.
This is a critical gap in many coverage plans. If your parent co-signed your student loans and you die, your parent could face collection calls and wage garnishment. Life insurance for parents with a mortgage and student loans should include enough coverage to pay off those co-signed loans directly, removing the burden from your co-signer. When you calculate your death benefit, add the full balance of any co-signed student loans, even if you believe they would be discharged. It is better to have a surplus than to leave a co-signer exposed.
Also consider what happens to the co-signer's credit if the loan goes into default after your death. A life insurance payout can prevent that outcome by retiring the debt immediately. Speak with a licensed agent about how to structure your beneficiary designation so the funds can be used to pay off co-signed loans without delay.
Comparing Term Quotes Against Lender-Offered Products
Lenders and mortgage servicers often offer mortgage protection insurance or credit life insurance at closing. These products can be convenient, but they are rarely the most affordable or flexible option. Credit life insurance typically pays a benefit equal to the outstanding loan balance to the lender, not to your family. Mortgage protection may have a declining benefit and limited underwriting. A level term policy from a competitive carrier usually offers more coverage for the same or lower premium.
When comparing options, ask these questions:
- Does the policy pay a level death benefit that my family controls, or a declining benefit paid to the lender?
- Can the coverage be used for student loans, income replacement, and final expenses, or only the mortgage?
- Is the premium guaranteed for the full term, or can it increase?
- Does the policy require a medical exam, and how long does underwriting take?
Term quotes from multiple carriers give you a baseline for comparison. If a lender-offered product costs more and covers less, you can decline it with confidence. If you need help finding the best life insurance brokers near me today, our guide explains how to connect with licensed professionals who can shop multiple carriers on your behalf.
Remember that life insurance for parents with a mortgage and student loans should be reviewed every few years. If you refinance your mortgage, pay off student loans, or have another child, your coverage needs may change. A periodic review ensures your family remains protected without paying for coverage you no longer need.
Frequently Asked Questions
How much life insurance do I need if I have a mortgage and student loans?
Add your mortgage balance, student loan totals, and 10 to 15 times your income, then subtract savings and existing coverage. A licensed agent can help you refine the number based on your children's ages and your co-signer exposure.
Does life insurance pay off student loans automatically?
No. The death benefit is paid to your beneficiaries, who can use it to pay off student loans. If you want to ensure the loans are retired, name a trusted beneficiary and leave instructions, or consider a policy with a specific beneficiary designation for that purpose.
Can I get life insurance if I have a mortgage and student loans?
Yes. Having debt does not disqualify you from coverage. In fact, it makes coverage more important. Underwriters focus on your health, age, and lifestyle, not the size of your mortgage or student loans.
Is mortgage protection insurance enough?
Usually not. Mortgage protection covers only the mortgage and may pay the lender. A level term policy covers all your debts and income replacement, giving your family more flexibility.
What happens to my co-signer if I die with student loans?
It depends on the loan. Federal loans are often discharged, but private loans may leave the co-signer responsible. Life insurance can provide the funds to pay off those loans and protect your co-signer.
Life insurance for parents with a mortgage and student loans is a practical, affordable way to keep your family secure. Start by calculating your debt and income replacement needs, then compare term quotes from multiple carriers. With the right coverage in place, your family can stay in their home and your co-signer can avoid a financial burden. To get personalized quotes and speak with a licensed agent, call (833)-212-4240 or visit LifeInsurance-Quote.com today.