Life Insurance for Multi Generational Households: A Guide
Life insurance for multi generational households protects every generation. Call (833)-212-4240 to compare policies and close coverage gaps.
By Tarian Vex
Three generations under one roof can be a source of strength, shared resources, and deep family connection. It can also create a web of financial interdependence that few families fully map out until a crisis hits. When grandparents, parents, and children rely on one another for housing, childcare, income, or caregiving, the death of any one member can ripple through the entire household's stability. That is why life insurance for multi generational households deserves careful, deliberate planning rather than a one-size-fits-all policy purchased in haste.
The challenge is that a multi generational household does not have a single financial profile. The primary earner may carry the mortgage and health benefits, while a grandparent contributes retirement income and childcare, and a young adult may be building a career while helping with bills. Each role carries a different financial value and a different risk if that person dies. A thoughtful plan accounts for these differences and coordinates coverage so the household does not face a sudden shortfall in income, housing, or care.
This guide walks through how to map financial interdependence, prioritize coverage by role, use final expense and small whole life policies for older members, budget across multiple policies, and set beneficiary designations that prevent confusion in blended families. Along the way, it explains how to compare quotes without overpaying, and where to get personalized help if the household's needs are complex.
Mapping Financial Interdependence Across Three Generations
Before shopping for coverage, it helps to write down who pays for what and who depends on whom. Financial interdependence in a multi generational household often includes shared housing costs, pooled income, childcare, eldercare, and transportation. A grandparent may provide regular childcare that would otherwise cost thousands per month, while an adult child may cover the grandparent's groceries or medical copays. These contributions are easy to overlook because they are not always cash payments, but they have real replacement value.
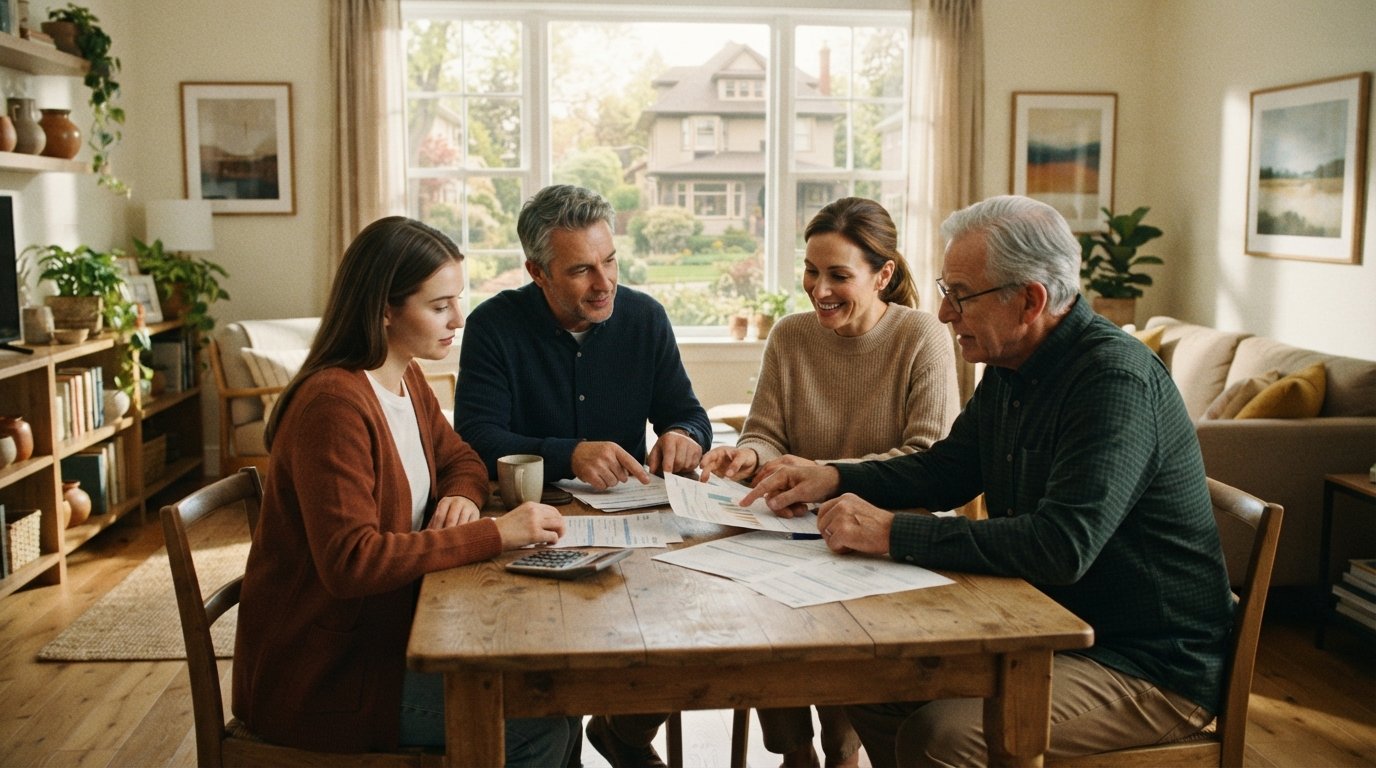
A simple mapping exercise can clarify the stakes. Gather the household adults and list each person, their income sources, their caregiving responsibilities, and the expenses they cover. Then ask what would happen financially if that person died tomorrow. The answers often reveal that the household is more dependent on certain members than anyone realized, and that some members have no coverage at all.
Consider a household with two working parents, two children, and a grandmother who receives Social Security and provides after-school care. The parents carry term policies through work, the grandmother has no coverage, and the family has no plan for funeral costs. If the grandmother dies, the family loses childcare and faces final expense bills. If a parent dies, the surviving parent may need to reduce work hours. Mapping these scenarios makes the coverage gaps visible and gives the family a starting point for prioritizing policies.
It also helps to distinguish between income replacement and obligation replacement. Income replacement covers the wages a person would have earned. Obligation replacement covers debts, caregiving, housing, and final expenses that the household would still need to handle. A grandparent on a fixed income may have little income to replace but significant obligation replacement value through childcare and shared housing contributions. That distinction shapes which policy types make sense for each generation.
Coverage Priorities for the Primary Earner Versus Older Members
The primary earner usually needs the largest death benefit because their income supports the household's largest fixed costs. A term life policy sized to cover the mortgage, outstanding debts, childcare or education costs, and several years of household income is typically the core of the plan. Term coverage is often the most affordable way to buy a large benefit for a defined period, such as until the children are grown or the mortgage is paid off.
Older household members have different priorities. If a grandparent provides caregiving or contributes to household expenses, a modest term or whole life policy can protect that contribution. If the grandparent is retired with limited income, the priority often shifts to final expense coverage: a small whole life policy that covers funeral costs, medical bills, and small debts so the family does not have to scramble. These policies are usually easier to qualify for and can provide peace of mind without a large premium commitment.
Young adults in the household, whether they are adult children or grandchildren, may need coverage if their income supports shared expenses or if they have co-signed debts. Even a small policy can prevent a student loan or car loan from becoming a burden for parents who co-signed. The key is to match the policy to the role, not to buy the same product for everyone.
Here is a practical way to prioritize coverage across the household:
- Primary earner: A term policy sized to replace income and cover major debts, plus a supplemental policy if the earner has significant caregiving responsibilities.
- Secondary earner or working adult child: A term policy sized to cover their share of household expenses and any co-signed debts.
- Grandparent with caregiving or income contributions: A small whole life or term policy that protects their contribution and covers final expenses.
- Grandparent without financial contributions: A final expense policy to cover funeral and medical costs, which protects the household from a sudden bill.
- Young adults with shared expenses: A modest term policy to cover co-signed debts and their share of housing costs.
After listing these priorities, the household can compare quotes for each role rather than trying to find one policy that fits everyone. This approach usually produces better coverage at a lower total cost because each person buys only what they need.
Final Expense and Small Whole Life Policies for Grandparents
Final expense insurance, sometimes called burial insurance, is a small whole life policy designed to cover funeral costs, medical bills, and other end-of-life expenses. For grandparents in a multi generational household, these policies serve two purposes: they ensure a dignified funeral without draining household savings, and they prevent a grief-stricken family from making rushed financial decisions. The average funeral with burial can cost several thousand dollars, and that figure does not include medical bills or outstanding debts.
Small whole life policies have features that make them practical for older applicants. They typically have fixed premiums that do not increase with age, a death benefit that does not expire as long as premiums are paid, and simplified underwriting that may not require a medical exam. Some policies are available with guaranteed acceptance, though those often have a graded death benefit during the first few years. For grandparents who are in reasonable health, a simplified issue policy may offer a better value than a guaranteed acceptance policy.
It is important to size the policy realistically. A final expense policy should cover the expected funeral costs, any known medical bills, and a small buffer for unexpected expenses. Buying more than that can strain a fixed income, while buying too little leaves the family to cover the difference. Reviewing the policy every few years as costs change helps keep the coverage aligned with actual needs.
For families with tight budgets, it helps to compare quotes for final expense coverage before buying. Our guide on affordable life insurance plans explains how to reduce premiums without sacrificing the protection that matters most. The same principles apply when shopping for grandparents: compare multiple offers, check the underwriting requirements, and confirm the death benefit is enough to cover the expenses the family would actually face.
Budgeting a Single Household Plan Across Multiple Policies
Multiple policies do not have to mean multiple financial headaches. The key is to treat the household's coverage as a single budget line, then allocate premium dollars where they provide the most protection per dollar. Start with the primary earner's term policy, since it protects the largest financial risk. Then add coverage for other members in order of financial impact, and adjust as the household's needs change.
Here is a step-by-step budgeting process that works for many multi generational households:
- Total the household's essential annual expenses, including housing, food, utilities, childcare, eldercare, and debt payments.
- Identify which expenses would continue if each member died, and for how long.
- Set a coverage target for each member based on the expenses they support or the obligations they leave behind.
- Compare quotes for each coverage target, prioritizing term policies for large benefits and small whole life policies for final expenses.
- Set a total premium budget that fits comfortably within the household's monthly cash flow, then adjust coverage amounts rather than dropping policies entirely.
After the policies are in place, review them once a year or after major life events such as a birth, a death, a marriage, or a change in income. Premiums and coverage needs shift over time, and a policy that fit five years ago may no longer match the household's situation. A brief annual review keeps the plan aligned with reality and prevents gaps from opening quietly.
For households that want to compare multiple options quickly, a quote comparison service can save hours of individual outreach. USLifeQuote connects consumers with licensed insurance agents who can analyze the household's needs and suggest plans at affordable costs. That is especially useful when the household needs several policies with different underwriting requirements, because an agent can help coordinate the applications and avoid duplicate medical exams.
Beneficiary Designations That Avoid Confusion in Blended Households
Beneficiary designations are where many multi generational households run into trouble. In a blended family, it is common for a parent to want to provide for a new spouse while also protecting children from a prior relationship. Without clear designations, the death benefit may go to someone the deceased did not intend, or the family may face disputes that delay the payout. Life insurance beneficiary designations generally override a will, so getting them right is essential.
The first step is to name primary beneficiaries and contingent beneficiaries for every policy. A primary beneficiary receives the death benefit first, and a contingent beneficiary receives it if the primary beneficiary has already died. Naming both prevents the payout from going through probate or being determined by default rules. For blended families, it is often wise to name specific individuals rather than relying on a generic class designation such as "my children," which can create ambiguity if there are stepchildren or children from different relationships.
Trusts can be useful when the household wants more control over how and when the benefit is distributed. A trust can hold the death benefit for minor children, provide for a surviving spouse while preserving assets for children from a prior marriage, or coordinate with special needs planning so a beneficiary does not lose eligibility for needs-based benefits. Because trust rules vary by state, it is best to work with an estate planning attorney when the household's situation is complex.
It also helps to review designations after major life events. A divorce, remarriage, birth, or death can change who should receive the benefit, and outdated designations are a common source of family conflict. Keeping a simple record of each policy, its beneficiaries, and the date of the last review makes it easier to keep everything current.
Coordinating Coverage Without Overlapping Protection
Multi generational households sometimes over-insure one member while leaving another completely uncovered. That often happens when one person buys a large policy through work and assumes the whole family is protected. Employer coverage is a good start, but it is usually tied to the job and may not be portable if the person leaves or retires. It also may not be enough to replace income and cover debts.
A coordination review helps the household see the full picture. List every policy, including employer-provided coverage, and note the death benefit, premium, and beneficiary for each. Then compare the total coverage against the household's actual needs. If the primary earner is over-insured relative to the household's expenses, the family may be able to reduce that policy and redirect the premium toward a grandparent's final expense coverage or a young adult's term policy.
The goal is not to buy the most coverage but to close the gaps that would cause the most financial harm. A household with a paid-off mortgage and substantial savings may need less income replacement than a household with a large mortgage and young children. A household with a grandparent in fragile health may need more final expense coverage than one with a healthy grandparent who has savings set aside. Matching coverage to the household's specific risks is the most efficient way to protect everyone.
For families that want help sorting through these tradeoffs, working with a licensed agent can simplify the process. An agent can review the household's policies, identify gaps, and recommend coverage amounts that fit the budget. That guidance is especially valuable when the household includes members with health conditions, because underwriting rules vary widely among carriers.
Life insurance for multi generational households works best when it is treated as a household plan rather than a collection of individual purchases. By mapping financial interdependence, prioritizing coverage by role, using final expense policies for grandparents, budgeting across multiple policies, and setting clear beneficiary designations, a family can protect every generation without overpaying. The plan does not need to be complicated, but it does need to be deliberate, reviewed regularly, and adjusted as the household changes.