Life Insurance for Freelancers and Gig Workers: A 2026 Guide
Life insurance for freelancers and gig workers protects your family when employer benefits vanish. Call (833)-212-4240 for expert guidance.
By Orin Valtor
You have traded the predictable paycheck for freedom, but that freedom comes with a hidden cost: no employer-sponsored benefits. When you get sick, there is no paid time off. When you retire, there is no 401(k) match. And if you die, there is no group life insurance policy to cushion the blow for your family. For the self-employed, the safety net is yours to build. Life insurance for freelancers and gig workers is not a luxury; it is the foundation of a financial plan that protects the people who depend on your income, no matter how irregular that income may be.
The challenge is that the traditional life insurance playbook was written for people with W-2 jobs. Underwriters want stability. Freelancers live with variability. Gig workers juggle multiple 1099s. The good news is that the insurance industry has adapted, and there are now clear paths to coverage that fit the realities of independent work. This guide will walk you through why employer coverage disappears, how to choose a policy that smooths out your cash flow, what insurers really think about your side hustles, and how to budget premiums when your income looks different every month.
Why Employer Group Coverage Rarely Follows the Self-Employed
When you leave a full-time job, your group life insurance typically ends on your last day of employment. You may be offered a conversion option, but it often comes with a hefty price tag and limited flexibility. For freelancers and gig workers, this means starting from scratch. There is no HR department to enroll you, no payroll deduction to automate the payment, and no employer contribution to lower your cost. You are entirely responsible for finding and funding your own coverage.
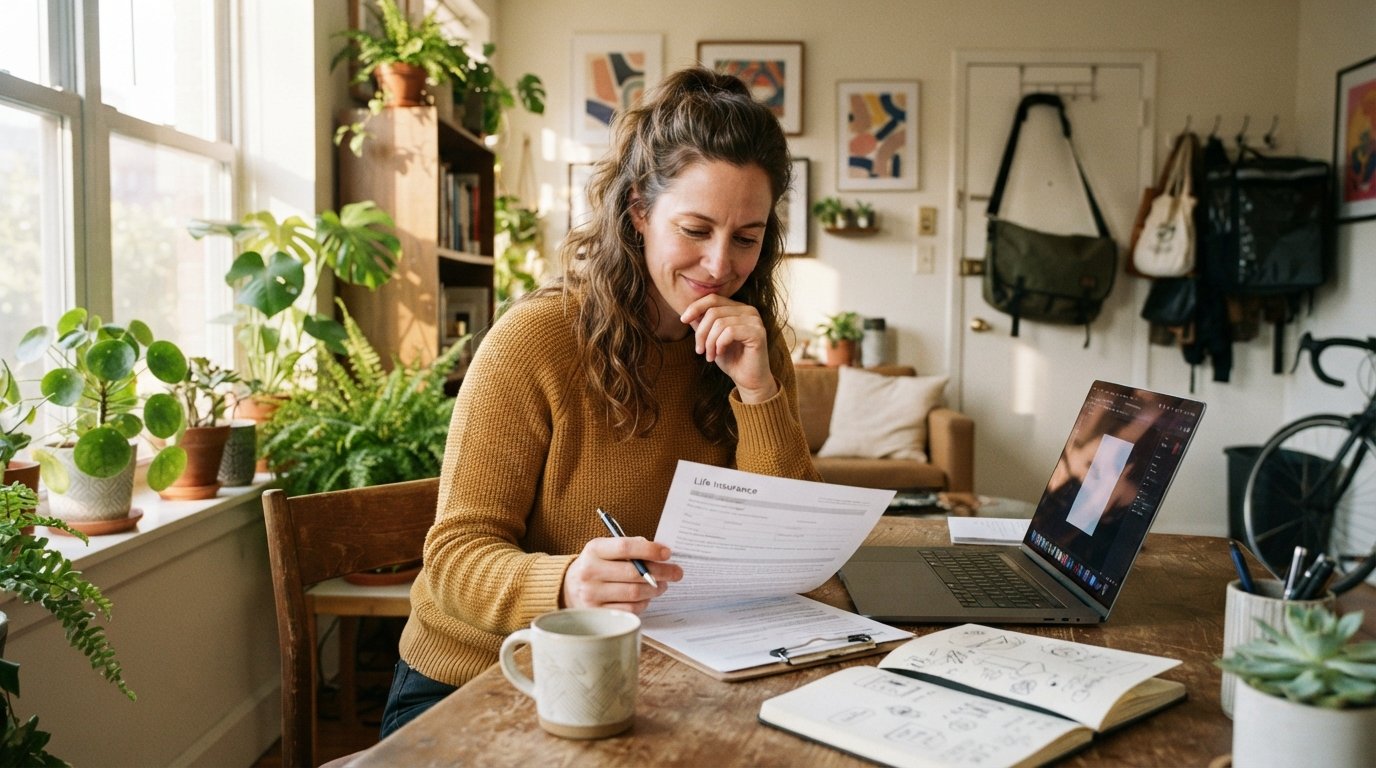
This gap is more than a minor inconvenience. Group life insurance is often a multiple of your salary, and it is priced based on the entire workforce, which can be cheaper for older or less healthy employees. As an independent worker, you are individually underwritten. Insurers will look at your health, your age, and your hobbies, but they will also scrutinize your income. Without an employer verifying your salary, they need other ways to confirm that you have insurable financial value. That is why freelancers often need to provide tax returns, 1099 forms, or bank statements during the application process.
The lack of employer coverage also means you cannot rely on automatic enrollment. You have to be proactive. The first step is to acknowledge that the safety net is gone and that replacing it is a priority. Many freelancers delay life insurance because they are focused on cash flow, but the cost of waiting can be significant. Premiums rise with age, and a health issue that develops later can make coverage unaffordable or impossible to obtain. Treating life insurance as a non-negotiable business expense, just like your laptop or your internet bill, is the mindset shift that makes it happen.
Choosing Guaranteed Level Premiums to Smooth Irregular Income
Freelancers and gig workers often experience income that swings wildly from month to month. A strong quarter might be followed by a dry spell. This variability makes budgeting a challenge, and it makes the structure of your life insurance policy especially important. The most common recommendation for independent workers is a term life insurance policy with guaranteed level premiums. This means the amount you pay each month stays the same for the entire term of the policy, whether that is 10, 20, or 30 years.
Level premiums provide predictability. You know exactly what your insurance will cost in January and in July, regardless of whether you landed a big contract or had a slow month. This predictability is valuable for cash flow planning. It also protects you from future rate increases due to age or minor health changes. If you choose a policy with a renewable term, the premium will increase at each renewal, which can be stressful when you are already managing variable income. A guaranteed level term policy locks in your rate and removes that uncertainty.
Another option is permanent life insurance, such as whole life or universal life, which builds cash value over time. While these policies can be useful for estate planning or long-term savings, they come with higher premiums and more complexity. For most freelancers and gig workers, term life insurance offers the best balance of affordability and protection. It covers the years when your family is most dependent on your income, such as when you have a mortgage or young children. You can always supplement with permanent coverage later if your financial situation improves.
When comparing term policies, pay attention to the conversion privilege. Some term policies allow you to convert to permanent coverage later without a new medical exam. This can be a valuable safety valve if your health changes. Also, check the policy's riders, such as a waiver of premium rider, which can keep your coverage in force if you become disabled and cannot work. For freelancers, who do not have employer-provided disability insurance, this rider can be a crucial layer of protection.
How Insurers Treat Multiple Income Streams and 1099 Earnings During Underwriting
Underwriting is the process insurers use to assess risk. For freelancers and gig workers, the income verification step can feel intrusive, but it is necessary because there is no employer to confirm your salary. Insurers want to see that your income is stable enough to support the coverage amount you are requesting. They also want to ensure that the coverage is proportional to your financial need, which is why they may ask for tax returns, 1099 forms, and bank statements.
Having multiple income streams can actually be an advantage. Insurers view diverse income sources as a sign of resilience. If one client dries up, you have others to fall back on. However, you need to document those streams clearly. For example, if you earn money from freelance writing, consulting, and driving for a rideshare app, you should be prepared to show consistent earnings from each source over the past two to three years. Lenders and insurers typically average your income over time, so a single strong year may not be enough to justify a large policy.
If your income has been inconsistent, do not panic. Many insurers are accustomed to working with self-employed applicants. They may ask for additional documentation or conduct a phone interview to understand your business model. The key is to be transparent and organized. Keep separate bank accounts for your business and personal finances, and maintain records of your contracts and invoices. This not only helps with underwriting but also makes tax season easier. If you are unsure which insurers are most friendly to freelancers, working with a broker who specializes in self-employed clients can save you time and frustration. You can find the best life insurance brokers near me to get personalized guidance through the underwriting process.
It is also worth noting that some insurers offer simplified issue or guaranteed issue policies that do not require income verification or a medical exam. These policies are easier to obtain but come with lower coverage amounts and higher premiums per dollar of coverage. They can be a good stopgap measure if you need coverage quickly, but for most freelancers, a fully underwritten term policy will provide better value in the long run.
Budgeting a Monthly Premium Around Variable Cash Flow
The biggest hurdle for many freelancers is not qualifying for life insurance; it is fitting the premium into an unpredictable budget. When your income varies, a fixed monthly bill can feel like a burden during lean months. The solution is to treat your premium as a non-negotiable fixed expense, just like your rent or mortgage. This requires some planning, but it is achievable with a few simple strategies.
First, calculate your premium based on your average monthly income, not your highest month. It is tempting to buy a larger policy when you land a big contract, but you need to be able to sustain the payments during slow periods. A good rule of thumb is to keep your total life insurance premium under 5% of your average monthly income. If you have a particularly strong month, you can set aside the extra money in a dedicated savings account to cover premiums during future dry spells. Some insurers also offer annual payment options, which can save you money and reduce the number of transactions you need to manage.
Here are a few budgeting tactics that work well for variable income:
- Pay yourself a regular salary: Set up a separate business account and transfer a fixed amount to your personal account each month. Pay your life insurance premium from that personal account, so it feels like a regular bill.
- Use a proportional budget: Allocate a percentage of each payment you receive to fixed expenses, including insurance. For example, every time you deposit a client payment, immediately move 10% to a bills account that covers your premium.
- Build a premium buffer: Aim to save three to six months of premium payments in an emergency fund. This cushion ensures you never miss a payment, even during a slow quarter.
- Review your coverage annually: As your income grows, you may be able to afford more coverage. Conversely, if your income drops, you can adjust your policy or term length to keep premiums manageable.
Another consideration is the payment frequency. Monthly payments are convenient, but some insurers charge a small fee for installment plans. Paying annually or semi-annually can reduce your overall cost. If you choose monthly, set up automatic payments from an account that you do not use for discretionary spending. This reduces the risk of late payments and lapses in coverage. For freelancers, consistency is key. A lapsed policy is worse than no policy at all, because you lose the protection you have already paid for.
Finally, do not overlook the value of comparison shopping. Premiums for the same coverage can vary significantly between insurers. Using a platform that provides multiple quotes from licensed agents can help you find the most affordable option for your specific situation. For a seamless way to compare personalized quotes and connect with agents who understand self-employed income, you can get a free life insurance quote and see how much you could save. Taking the time to compare offers is one of the most effective ways to keep your premium low without sacrificing coverage.
Life insurance for freelancers and gig workers is not just about death benefits; it is about peace of mind. It allows you to pursue your independent career without constantly worrying about what would happen to your family if the unexpected occurs. By understanding how underwriting works, choosing level premiums, documenting your income streams, and budgeting strategically, you can secure the protection you need without destabilizing your finances. The effort you put in today will pay off in security for the people you love.