Life Insurance for Families with a Stay at Home Parent
Life insurance for families with a stay at home parent protects unpaid caregiving. Call (833)-212-4240 to compare quotes for both parents in one request.
By Lunara Voss
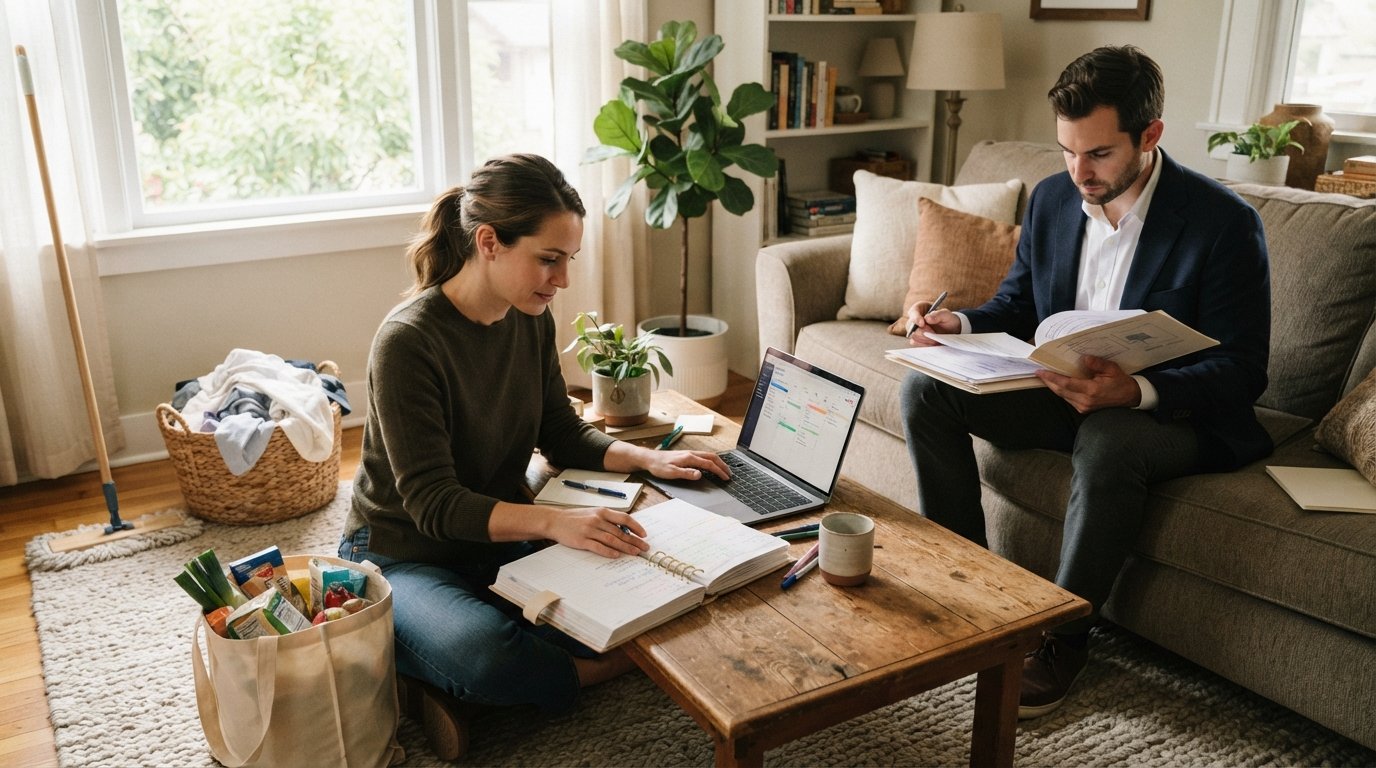
Imagine a single-income household where one parent earns the paycheck and the other runs the home. If the stay at home parent died tomorrow, the surviving spouse would suddenly need to pay for childcare, transportation, meal preparation, cleaning, and homework help, all while grieving and holding down a job. That is the hidden financial risk that life insurance for families with a stay at home parent is designed to solve. Even though no salary appears on a tax return, the unpaid work of a caregiver has real market value, and replacing those services can cost tens of thousands of dollars per year. This article explains how to quantify that value, choose the right policy type and amount, and compare quotes for both parents without overpaying.
Why a Stay at Home Parent Needs Life Insurance
Many families assume that life insurance is only for the breadwinner. After all, the logic goes, if no income is lost, there is no financial gap to fill. That reasoning ignores the cost of outsourcing the services a stay at home parent provides. Childcare alone can run $10,000 to $20,000 per child annually in many parts of the country, and that is before you add after school care, summer camps, and sick day coverage. Add transportation, grocery shopping, cooking, cleaning, laundry, and household administration, and the replacement cost climbs quickly. A 2023 study by Salary.com estimated the market value of a stay at home mother's work at over $180,000 per year when all roles were counted, and while that figure is a theoretical composite, it illustrates the scale of the exposure.
Life insurance for families with a stay at home parent converts that invisible labor into a visible safety net. The death benefit gives the surviving spouse the freedom to hire help, reduce work hours, or take unpaid leave without facing financial ruin. It also protects the family's standard of living during an emotionally devastating period. Without coverage, the working parent might be forced to choose between a paycheck and being present for grieving children, a choice no family should have to make.
There is another angle that is easy to overlook: the stay at home parent often manages the household's financial administration, from paying bills to coordinating medical appointments. If that person dies, the surviving spouse may need to pay for professional services such as tax preparation, financial planning, or daily money management. Life insurance proceeds can cover those costs and provide a buffer while the family reorganizes.
How to Value Unpaid Caregiving in Coverage Terms
You do not need an exact accounting degree to estimate the value of a stay at home parent's contributions, but you do need a structured approach. The goal is to translate daily tasks into annual replacement costs, then multiply by the number of years the family would need help. Start by listing the services the stay at home parent provides and researching local market rates for each. Then add a margin for the surviving spouse's reduced work capacity, since grief and single parenting often lead to lower earnings or higher expenses.
Here is a simple framework you can use to build a coverage estimate:
- Childcare: Full time care for each child until school age, plus before and after school care and summer coverage until the children are independent.
- Transportation: School runs, activities, and errands, valued at a per mile or hourly rate.
- Household management: Cleaning, laundry, cooking, and home maintenance, priced at local service rates.
- Administrative support: Bill paying, appointment scheduling, and tax preparation, which may require professional help.
- Buffer for reduced earnings: A lump sum to cover the surviving spouse's potential drop in income or need for unpaid leave.
Once you have annual replacement costs, multiply by the number of years until your youngest child turns 18 or finishes college. For example, if replacement services cost $40,000 per year and you have 15 years until your youngest child is independent, the raw need is $600,000. Add the buffer for reduced earnings and any outstanding debts, then subtract existing savings and other coverage. That gives you a starting death benefit for the stay at home parent. The same exercise for the working parent will often show a lower need than expected, because the stay at home parent's continued caregiving offsets some of the childcare costs that would otherwise appear in the working parent's calculation.
Why the Working Spouse May Need Less Coverage Than Expected
Conventional wisdom says the breadwinner needs the largest policy. In a single income family, that is often true, but the math is more nuanced than a simple multiple of salary. If the stay at home parent survives, the family does not need to pay for childcare, after school care, or many household services. The working parent's death creates an income gap, but it does not create a full time caregiving gap. As a result, the working spouse's coverage can be sized to replace income, pay off the mortgage, and fund education, without automatically adding years of childcare costs that the surviving stay at home parent would provide.
That said, the working spouse still needs robust coverage. The family loses a salary, employer benefits, and future retirement contributions. A common approach is to multiply income by 10 to 15, then add the mortgage balance and education costs, and subtract savings and existing coverage. The result is often still substantial, but it may be less than the stay at home parent's policy once caregiving replacement costs are counted. This is why quoting both parents in one comparison request matters: it reveals the true cost of insuring each life and helps you allocate your premium budget where the risk is greatest.
There is also a practical reason to insure both parents. If both die in a common accident, the guardians of your children would face the full cost of raising them without either parent's caregiving or income. A modest policy on the stay at home parent ensures that the guardian has resources to provide childcare, housing, and education. Even if the probability is low, the consequence is severe, and the premium for a healthy stay at home parent is often surprisingly affordable.
Term Policies Sized to the Years Before Children Are Independent
For most families with young children, term life insurance is the most efficient way to cover the caregiving gap. Term policies last for a set number of years, typically 10, 15, 20, or 30, and they pay a death benefit only if the insured dies during that period. Because term coverage has no cash value component, it is far cheaper than permanent insurance for the same death benefit. That affordability matters when you are trying to insure two parents on one income.
The key is to match the term length to the years of dependency. If your youngest child is two years old, a 20 year term policy covers the family until that child is 22, which aligns with college graduation. If you have a newborn and plan for private college, a 25 or 30 year term may be appropriate. You can also ladder policies: buy a 20 year term for the bulk of the need and a 30 year term for a smaller amount to cover the tail end of dependency. Laddering can reduce premiums while keeping coverage aligned with the family's timeline.
When comparing term quotes for a stay at home parent, pay attention to the conversion privilege. Some term policies allow you to convert to permanent coverage later without a new medical exam. That feature can be valuable if the stay at home parent develops a health condition that would otherwise make them uninsurable. Also check the renewal terms: a policy that is guaranteed renewable lets you keep coverage after the term ends, though at a higher premium. For most families, a straightforward level term policy with a conversion option is the best balance of cost and flexibility.
Riders That Cover a Caregiver's Death or Disability
Standard life insurance pays a death benefit, but some riders can enhance protection for a caregiving parent. A child rider, for example, provides a small death benefit if a child dies, which can cover funeral expenses and counseling. That is not the same as insuring the caregiver, but it is a common add on for families. More relevant are riders that address the caregiver's disability, since a stay at home parent who becomes disabled may need to pay for the very services they once provided.
Disability income insurance is separate from life insurance, but some life policies offer a disability waiver of premium rider. If the insured becomes totally disabled, the insurer waives the premiums so the policy stays in force. That is valuable for a stay at home parent because it keeps the death benefit intact during a period when the family may be paying for additional care. Another option is a long term care rider or a chronic illness rider, which can accelerate the death benefit if the insured needs extended care. These riders are not a substitute for standalone long term care insurance, but they can provide flexibility.
For caregivers, an accelerated death benefit rider is often included at no extra cost. It allows the insured to receive a portion of the death benefit early if diagnosed with a terminal illness. That money can be used for experimental treatment, home modifications, or to pay for childcare while the parent is undergoing treatment. When you request quotes for life insurance for families with a stay at home parent, ask the licensed agent which riders are available and how they affect the premium. Not every rider is worth the cost, but a waiver of premium and an accelerated death benefit are usually sensible for a caregiving parent.
How Both Parents Can Be Quoted in One Comparison Request
Comparing life insurance for two parents used to mean two separate applications, two medical exams, and two rounds of underwriting. Today, a single quote request can capture information for both parents and return multiple options from licensed agents. The process is straightforward: you enter basic details for each parent, including age, tobacco use, health history, and the coverage amount you are considering. The platform then connects you with participating agents who can provide customized quotes. You do not need to complete a medical exam to see preliminary rates, and you are not obligated to buy.
To get the most useful comparison, gather the following information before you start:
- Each parent's date of birth, height, weight, and tobacco status.
- A rough estimate of the death benefit needed for each parent, based on the caregiving and income replacement calculations above.
- Any known health conditions, medications, or family history that could affect underwriting.
- Your budget for total monthly premiums across both policies.
Once you have quotes, compare them on more than just price. Look at the insurer's financial strength rating, the conversion privilege, the riders included, and the underwriting class you qualify for. A slightly higher premium from a highly rated insurer with a strong conversion option may be worth it for a stay at home parent who plans to return to the workforce later. If you want help interpreting the options, you can find life insurance agents near me who specialize in family coverage and can walk you through the trade offs.
When you are ready to see personalized numbers, USLifeQuote provides a free comparison tool that connects you with licensed agents who can quote both parents in one request. The service is designed to help families find affordable coverage without pressure, and it can be especially helpful when you are trying to balance two policies on a single income. Remember that eligibility and rates vary by carrier and agent, so the quotes you receive are personalized to your situation rather than guaranteed.
Common Mistakes Families Make with Stay at Home Parent Coverage
One of the most common mistakes is skipping coverage on the stay at home parent entirely. Families sometimes rationalize that the working spouse's policy is enough, but that leaves the surviving caregiver without resources to replace the lost labor. Another mistake is underestimating the duration of need. A policy that expires when the youngest child is 10 may leave the family scrambling during the expensive teenage years. Match the term to the full dependency period, including college if you plan to help with costs.
A third mistake is buying only permanent insurance when term would suffice. Whole life and universal life policies can be useful for estate planning or lifelong needs, but they cost significantly more per dollar of death benefit. For a young family on a budget, term coverage usually provides the most protection for the premium. You can always add permanent coverage later as your finances grow. Finally, avoid naming minors as direct beneficiaries without a guardian or trust arrangement. A court may need to appoint a conservator to manage the money, which can delay access and add costs. Consult an estate planning attorney to set up a guardian and trust if your children are young.
Life insurance for families with a stay at home parent is not about replacing a salary; it is about protecting the unpaid work that keeps a household running. By valuing caregiving, sizing term coverage to the years of dependency, and comparing quotes for both parents in one request, you can build a safety net that reflects your family's real risks. Start with a simple estimate, gather your information, and request personalized quotes from licensed agents who can help you find affordable coverage. Your family's financial security is worth the conversation.