Life Insurance for Expecting Parents: Secure Coverage Early
Secure life insurance for expecting parents before the baby arrives. Call (833)-212-4240 to compare affordable quotes and lock in low rates today.
By Tavira Solen
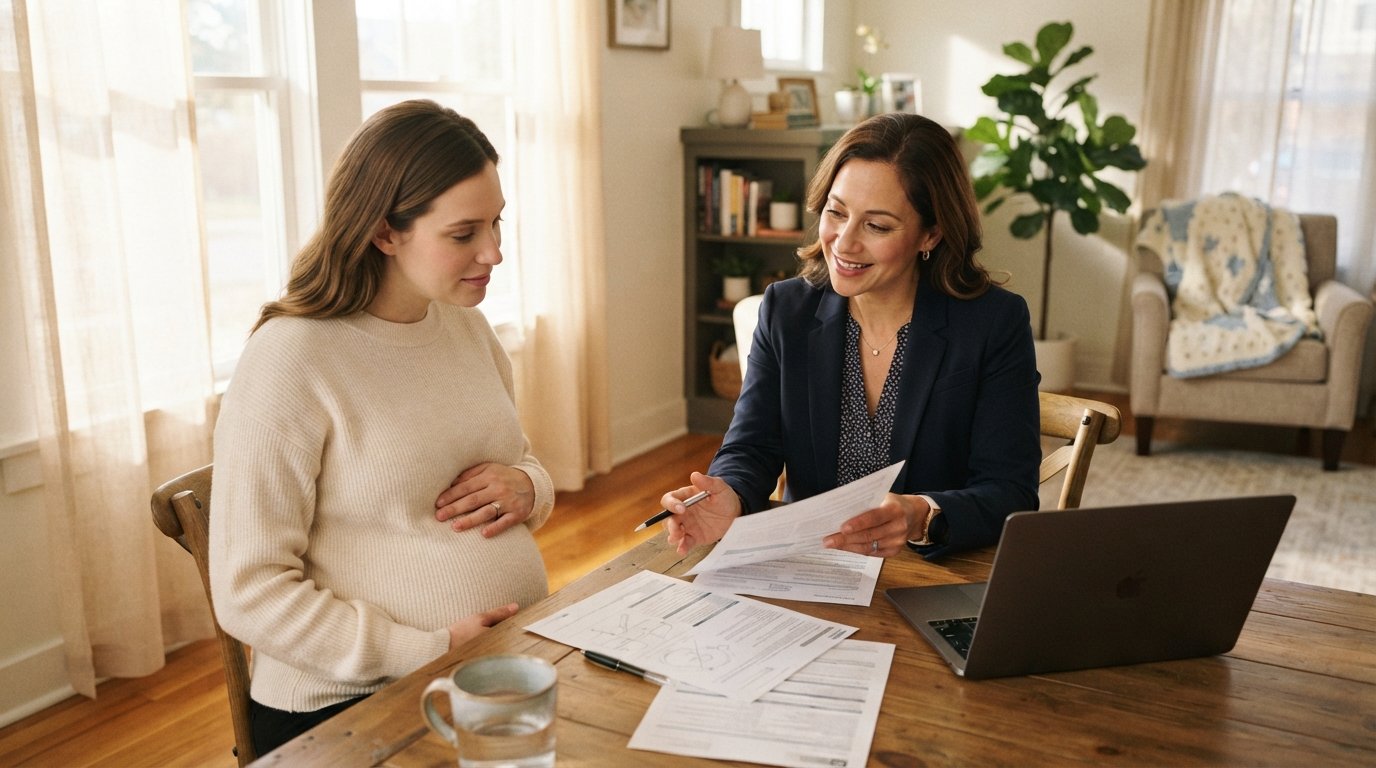
Expecting a baby is a time of joy, anticipation, and a long list of preparations. Between nursery planning and doctor visits, life insurance might not be at the top of your mind. But securing coverage before your baby arrives is one of the smartest financial moves you can make. Life insurance for expecting parents before the baby arrives ensures that your growing family is protected from day one, and it can be easier and more affordable to obtain now than later. In this guide, we will walk you through why timing matters, how to size your coverage, and the practical steps to get protected before your little one arrives.
Why Life Insurance for Expecting Parents Before the Baby Arrives Is Easier and Cheaper
When you apply for life insurance, insurers evaluate your health, age, and lifestyle. During pregnancy, many women experience temporary health changes such as gestational diabetes or pregnancy-induced hypertension. While these conditions often resolve after delivery, they can complicate underwriting and lead to higher premiums or even temporary declines. By securing coverage before these issues arise, you can lock in lower rates and avoid the hassle of explaining pregnancy-related complications.
Additionally, age is a major factor in life insurance pricing. The younger and healthier you are, the less you will pay. If you wait until after the baby is born, you might be a year or two older, and your health profile could have changed. Applying now means you can capitalize on your current health status and secure affordable coverage for the long term.
For expecting parents, life insurance is not just about covering final expenses; it is about replacing income and providing for your child's future. If something were to happen to one or both parents, the policy payout could cover childcare, education, and daily living expenses. That peace of mind is invaluable, and it is more accessible before the baby arrives.
How Much Coverage Do You Need?
Sizing your life insurance policy correctly is crucial. You want enough coverage to protect your family without overpaying for unnecessary benefits. For expecting parents, consider the immediate costs of delivery and early childcare, as well as long-term needs like education and income replacement.
Start by estimating your current and future expenses. Delivery costs can vary widely depending on your insurance and location, but even with good health insurance, out-of-pocket expenses can be significant. Then think about childcare, which can cost thousands of dollars per year. Add to that the ongoing costs of raising a child, such as food, clothing, and activities, plus future education expenses.
A common rule of thumb is to carry coverage equal to 10 to 15 times your annual income. However, this is just a starting point. You should also consider debts, mortgage, and any other financial obligations. For a more tailored approach, consider using a life insurance needs calculator or consult with a licensed agent who can help you determine the right amount.
Here are key factors to include when sizing your policy:
- Income replacement: How many years of your income would your family need to maintain their standard of living?
- Delivery and medical costs: Even with insurance, there may be deductibles and co-pays.
- Childcare and education: Estimate costs for daycare, school, and college.
- Debts and mortgage: Ensure your family can pay off major debts.
- Final expenses: Funeral and burial costs can average $10,000 or more.
By accounting for these factors, you can choose a coverage amount that provides real security for your family.
Timing Your Application Around Pregnancy and Medical Exams
If you are pregnant, you might wonder if you can still qualify for life insurance. The answer is generally yes, but the timing of your application can affect the process. Many insurers will approve pregnant applicants, but they may request additional information from your doctor, such as your due date and any complications.
It is often recommended to apply early in your pregnancy, before any potential health issues develop. If you are already in your third trimester, some insurers may postpone a decision until after delivery. However, simplified issue policies (which do not require a medical exam) may be available and can be approved quickly.
When you apply, be honest about your pregnancy and any related conditions. Non-disclosure can lead to claim denials later. If you have gestational diabetes, for example, the insurer may rate your policy differently, but it is better to disclose it upfront.
Consider these steps for a smooth application:
- Consult your doctor: Get a copy of your medical records and discuss any health changes.
- Choose the right policy type: Term life is often the most affordable for new parents, but permanent insurance may suit long-term needs.
- Apply early: Aim to submit your application before the third trimester to avoid delays.
- Be transparent: Disclose all health information, including pregnancy-related conditions.
- Work with a licensed agent: An agent can help you navigate underwriting and find the best rates.
If you are unsure where to start, using a quote comparison service can help you see options from multiple insurers. For instance, LifeAgency offers a platform to compare quotes from licensed agents, making it easier to find affordable coverage.
Naming Beneficiaries Before the Child Is Born
When you apply for life insurance, you will need to name a beneficiary. For expecting parents, this is a critical decision. You might name your spouse or partner as the primary beneficiary, and perhaps a trust for your child as a contingent beneficiary. However, minors cannot directly receive life insurance proceeds, so setting up a trust or appointing a guardian is essential.
Before the baby is born, you can name your spouse as the primary beneficiary and your estate or a trust as the contingent beneficiary. Once the child is born, you can update your beneficiary designation to include the child, but remember that a minor child will still need a guardian to manage the funds. Consult with an estate planning attorney to set up a trust if you want to ensure the money is used for your child's benefit.
It is also wise to review your beneficiary designations regularly, especially after major life events like birth or adoption. Keeping your policy up to date ensures that your wishes are honored and your family is protected.
Adding Coverage for Your Child After Birth
After your baby arrives, you may want to add coverage for them. Many life insurance policies offer the option to add a child rider, which provides a small amount of coverage for your children (typically $10,000 to $25,000) at a low cost. This can cover final expenses if the unthinkable happens, and some riders allow the child to convert to a permanent policy later in life.
Additionally, you can purchase a separate policy for your child, but this is usually not necessary unless you want to lock in coverage for their future insurability. A child rider is often the most cost-effective way to provide coverage for your children while they are minors.
When adding a child rider, you can typically do so without a medical exam, and the coverage can be added at birth or within a certain window (e.g., 30 days). Be sure to ask your insurer about the specifics.
Working with LifeInsurance-Quote.com
LifeInsurance-Quote.com is designed to help you compare life insurance quotes from multiple carriers and licensed agents. Our platform is free and easy to use: simply enter your ZIP code, age range, and tobacco use, and we will connect you with personalized quotes. We are not an insurance agency; we are a tool to help you shop smarter.
If you are looking for guidance on finding the best life insurance brokers, our article on finding the best life insurance brokers near me can provide valuable insights. Working with a broker can help you navigate the complexities of underwriting, especially during pregnancy.
Remember, securing life insurance for expecting parents before the baby arrives is a proactive step that provides peace of mind and financial security. By planning ahead, you can protect your family from day one.
Steps to Get Covered Now
If you are ready to secure coverage, follow these steps:
- Assess your needs: Use our guidelines to estimate how much coverage you need.
- Compare quotes: Use LifeInsurance-Quote.com to see offers from multiple insurers.
- Apply early: Submit your application before the third trimester to avoid delays.
- Be honest: Disclose all health information, including pregnancy-related conditions.
- Name beneficiaries: Decide who will receive the proceeds and consider a trust for your child.
- Review and update: After the baby is born, update your policy as needed.
By taking these steps, you can ensure that your family is protected no matter what the future holds.
Life insurance is a cornerstone of financial planning for growing families. It provides a safety net that allows your loved ones to maintain their lifestyle and pursue their dreams even if you are no longer there. Don't wait until after the baby arrives; take action now to secure affordable coverage and enjoy the peace of mind that comes with knowing your family is protected.