Life Insurance for Essential Workers and Trade Jobs
Life insurance for essential workers and trade jobs is within reach. Call (833)-212-4240 to compare quotes and protect your family today.
By Axion Vale
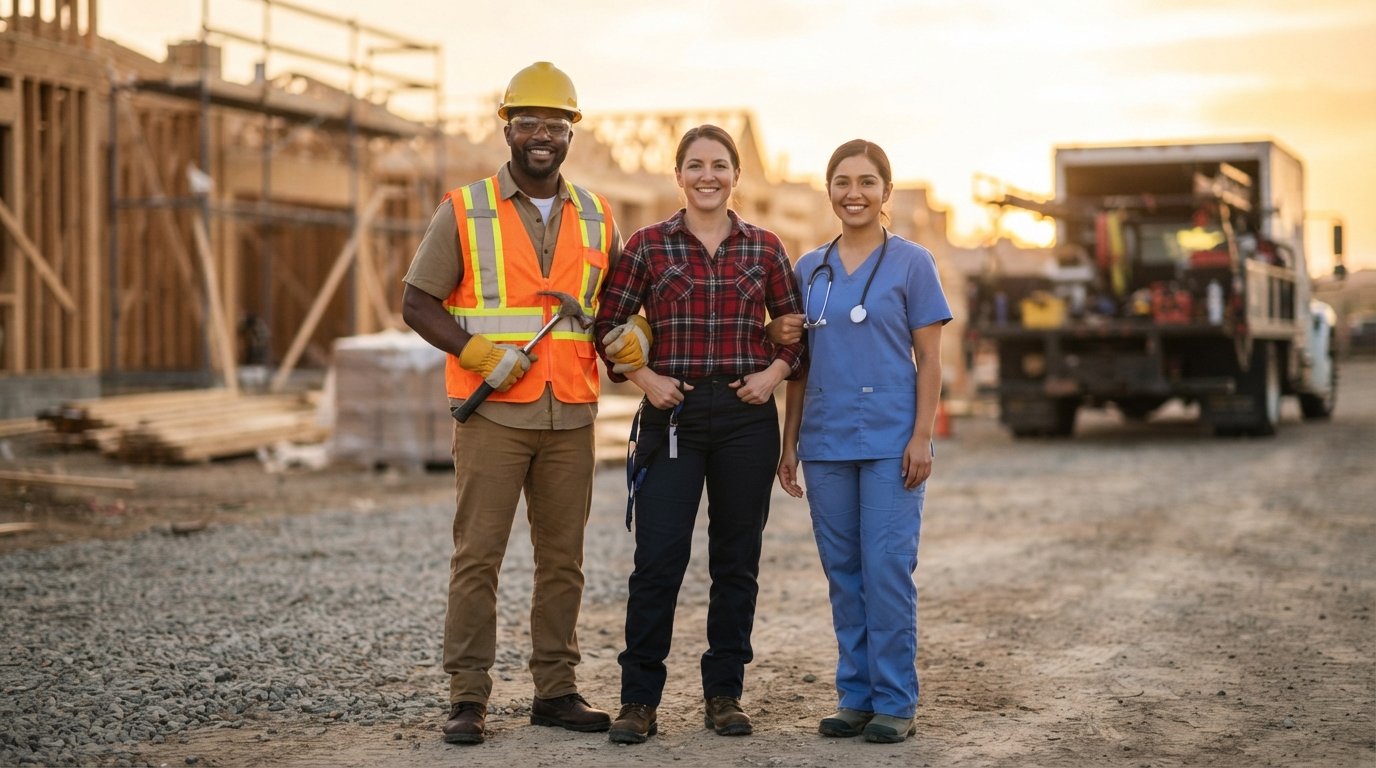
If you swing a hammer, drive a rig, or clock in at a hospital, your paycheck keeps the country running. But that same hands-on, high-stakes work can make you a puzzle for life insurance underwriters. Insurers see the daily risks you face and price accordingly, which is why life insurance for essential workers and trade jobs often comes with extra questions, occasional exclusions, and premium adjustments that office workers never encounter. The good news is that coverage is almost always available, and with the right approach, it can remain surprisingly affordable.
This guide breaks down how occupational risk classes work, which jobs trigger deeper underwriting, and how to build a coverage strategy that protects your family without overpaying. Along the way, you will learn how to request quotes that accurately reflect your trade, and how to avoid common mistakes that lead to denied claims or surprise rate increases.
How Insurers Classify Your Job and Why It Moves Your Premium
Life insurance companies use a system of occupational risk classes to estimate how likely a policyholder is to die during the coverage period. Most carriers use a scale that ranges from preferred (lowest risk) to standard, substandard, and sometimes table-rated categories for higher-risk occupations. A software engineer might land in a preferred class, while a commercial roofer could be classified as standard or substandard depending on the carrier and the specific duties described. The class assigned to you directly affects your premium, and in some cases, it determines whether you qualify for certain policy types at all.
The classification is not arbitrary. Underwriters look at injury and fatality statistics from sources like the Bureau of Labor Statistics, then adjust for the details of your actual job. Two electricians can end up in different classes if one works primarily in residential wiring and the other spends most days on high-voltage transmission towers. Similarly, a truck driver who hauls freight locally may be treated differently from a long-haul driver who covers mountainous routes at night. The more precisely you describe your duties, the more accurately the insurer can price your risk, and the less likely you are to face a surprise exclusion later.
It helps to understand the three broad tiers that most carriers use for occupational risk. The list below shows how the tiers generally break down, though individual insurers may use different labels or thresholds.
- Preferred or low-risk: Office-based roles, teachers, nurses in non-emergency settings, and most supervisory positions in construction or manufacturing.
- Standard or moderate-risk: Skilled trades such as carpentry, plumbing, electrical work, and light commercial driving, where injuries are possible but rarely fatal.
- Substandard or high-risk: Roofing, steel erection, logging, commercial fishing, high-voltage line work, and heavy equipment operation in volatile environments.
After you review those tiers, consider that the gap between standard and substandard pricing is often smaller than people fear. A roofer might pay 20 to 50 percent more than a carpenter for the same face amount, not double. The bigger issue is that some carriers simply will not write certain high-risk occupations, which is why comparing quotes from multiple insurers matters so much. A carrier that specializes in trade occupations may offer a standard rate where a mainstream insurer would assign a substandard class or decline the application entirely.
Jobs That Trigger Extra Underwriting or Exclusions
Certain occupations raise red flags for underwriters because they combine physical danger with unpredictable environments. If you work in one of these fields, expect additional questionnaires, a phone interview, or a request for details about safety protocols, equipment, and the percentage of time you spend on the most hazardous tasks. The extra scrutiny is not a rejection; it is the insurer's way of matching your premium to your actual risk profile.
Jobs that commonly trigger extra underwriting include commercial roofing, steel and ironwork, logging and forestry, commercial fishing and offshore work, high-voltage electrical line work, mining, and heavy equipment operation on construction sites. Emergency responders such as firefighters and paramedics also fall into this category, though many carriers offer specialized programs for first responders that recognize their training and safety records. Long-haul truck drivers may face additional questions about mileage, routes, and cargo type, while workers who handle explosives or work at heights above a certain threshold often see flat extra charges added to their base premium.
Exclusions are less common than extra underwriting, but they do exist. Some policies exclude death resulting from certain activities, such as aviation (if you are a pilot), scuba diving, or racing. For trade workers, the more relevant exclusions tend to involve specific job duties rather than hobbies. For example, a policy might exclude coverage if death occurs while working in an occupation not disclosed on the application. That is why honesty on the application is critical: if you tell the insurer you are a general laborer but you actually work on a high-rise scaffold, a claim could be contested.
There is also the question of disability and workers compensation overlaps. Many trade workers assume that workers compensation or employer-provided disability coverage is enough, but those benefits are limited. Workers compensation typically pays medical costs and a portion of lost wages for job-related injuries, but it does not pay a death benefit to your family if you die from a non-work-related cause. Disability insurance replaces part of your income if you are injured and cannot work, but it does not provide a lump sum to cover funeral costs, mortgage payments, or college tuition. Life insurance fills that gap, and it pays regardless of whether the death is work-related, as long as the policy is in force and the application was accurate.
Coverage Strategies for Workers with Hazardous Duties
Essential workers and trade professionals often need a mix of policy types rather than a single product. A term life policy is usually the foundation, because it provides the largest death benefit for the lowest premium during the years when your family is most financially vulnerable. A 20-year or 30-year term can cover the period until your mortgage is paid off and your children are independent, which is when the need for income replacement is highest. For many trade workers, a term policy with a face amount of $250,000 to $500,000 is both affordable and sufficient, though the right number depends on your debts, income, and family situation.
If you want coverage that lasts your entire life and builds cash value, a whole life or universal life policy may be worth considering, but expect higher premiums and stricter underwriting. Some carriers offer simplified-issue policies with no medical exam, which can be helpful if you have health issues or a busy schedule, but these policies often have lower face amounts and higher costs per thousand dollars of coverage. A licensed agent can help you compare the trade-offs between term, whole life, and simplified-issue options based on your occupation and budget.
Another strategy is to layer coverage. You might buy a base term policy through a fully underwritten carrier that specializes in your occupation, then add a smaller simplified-issue policy to cover final expenses or a specific debt. Layering can also help if you are declined for a fully underwritten policy: a simplified-issue or guaranteed-issue policy may still be available, even if the death benefit is smaller. The key is to avoid going without coverage while you shop for the best option.
If you are ready to see how your occupation affects your rates, you can compare personalized life insurance quotes from multiple carriers in one place. A platform that works with agents who understand trade occupations can save you hours of phone calls and help you avoid applications that are likely to be declined.
How to Request Quotes That Reflect Your Trade Occupation
Getting an accurate quote starts with an accurate description of your job. Instead of writing "construction worker," specify your trade, your typical duties, the height at which you work, the equipment you operate, and the percentage of time you spend on each task. If you are a welder, mention whether you work at ground level or on scaffolds, and whether you handle pressurized tanks. If you are a nurse, note whether you work in an emergency room, an operating room, or a clinic. These details help underwriters place you in the right risk class and reduce the chance of a post-claim dispute.
It also helps to work with an agent who has experience with your industry. An agent who regularly writes policies for electricians, roofers, or truck drivers will know which carriers are most favorable to your occupation and which ones are likely to add flat extra charges or decline. They can also tell you whether a particular carrier offers a preferred rate for workers who complete safety training or hold certifications, which can offset some of the occupational risk.
Before you apply, gather the documents you will need: your job description, any safety certifications, your driving record if you operate a vehicle, and details about any hazardous hobbies. If you have a history of injuries or workers compensation claims, be ready to explain them. Underwriters are not looking for perfection; they are looking for consistency and honesty. A well-documented application with a clear explanation of your duties is more likely to be approved at a favorable rate than a vague one that raises questions.
Finally, do not assume that a decline from one carrier is the end of the road. Different insurers have different appetites for occupational risk. A carrier that declines a commercial fisherman might be perfectly happy to insure a commercial electrician, and vice versa. Submitting applications to multiple carriers through an independent agent or a quote comparison platform increases your chances of finding a policy that fits both your risk profile and your budget.
Frequently Asked Questions
Can I get life insurance if I work in a high-risk trade?
Yes, in most cases. High-risk trades such as roofing, logging, and commercial fishing may require additional underwriting or come with higher premiums, but coverage is generally available. Some carriers specialize in these occupations and offer more competitive rates than mainstream insurers. The key is to apply with carriers that understand your trade and to describe your duties accurately.
Will my premium go up if I change jobs within my trade?
Possibly. If you move from a lower-risk role to a higher-risk one, such as from residential electrical work to high-voltage line work, you should notify your insurer. Some policies allow you to reclassify your occupation, which could increase your premium. Failing to disclose a change in duties could jeopardize a claim, so it is always better to update your information.
Does workers compensation replace life insurance?
No. Workers compensation covers medical costs and lost wages for job-related injuries, and it may pay a death benefit to dependents in some cases, but it does not provide the same level of financial protection as a life insurance policy. Life insurance pays a lump sum to your beneficiaries regardless of whether the death is work-related, and it can be used to cover mortgage payments, debts, and future expenses.
How can I lower my premium if I have a hazardous job?
You can lower your premium by choosing a term policy instead of permanent coverage, selecting a smaller face amount, improving your health through diet and exercise, and working with an agent who knows which carriers offer the best rates for your occupation. Some carriers also offer discounts for safety certifications or for workers who have not filed a workers compensation claim in a certain number of years.
Life insurance for essential workers and trade jobs is not a luxury; it is a practical way to protect the people who depend on your income. By understanding how occupational risk classes work, being transparent about your duties, and comparing quotes from multiple carriers, you can find coverage that fits your budget and gives your family peace of mind. Start by requesting quotes that reflect your actual job, and let a licensed agent guide you through the options that make the most sense for your situation.