Life Insurance for Business Owners: Protect Partners and Employees
Life insurance for business owners protecting partners and employees is essential. Call (833)-212-4240 to compare coverage and shield your company.
By Selene Viora
A business is more than a source of income. For many owners, it is the product of years of sacrifice, the payroll that supports families, and the promise of a secure future. But what happens to that promise if a key partner or essential employee dies unexpectedly? Without a plan, the result is often a chaotic scramble: frozen accounts, panicked buyouts, lost clients, and grieving families left to untangle a financial mess. Life insurance for business owners protecting partners and employees is not a luxury; it is the quiet infrastructure that keeps a company standing when the unthinkable happens. This guide walks through the three critical layers of business life insurance, from buy-sell funding to employee group benefits, and shows how to size them correctly.
The Hidden Risks That Threaten Business Continuity
Most business owners insure the physical assets: the building, the equipment, the inventory. Far fewer insure the human assets, the people whose knowledge, relationships, and decision-making drive revenue. When a partner dies, the surviving owners face two immediate problems. First, the deceased partner's heirs may inherit the ownership stake and want to cash out immediately. Second, the surviving owners may not have the liquid capital to buy that stake, forcing a fire sale or an unwanted new co-owner. Without a funded plan, the business can be torn apart by legal and financial pressure within weeks.
Key employees create a different but equally serious exposure. A top salesperson, a lead engineer, or a long-tenured operations manager often holds client relationships, institutional knowledge, and specialized skills that cannot be replaced overnight. The death of such a person can cause project delays, lost accounts, and a drop in productivity that ripples through the entire company. The cost of recruiting and training a replacement is only part of the story; the lost revenue and momentum can be far larger.
Finally, rank-and-file employees face their own financial risks. Many workers rely on employer-provided benefits as their primary safety net. Without group life coverage, a death in the workforce can devastate a family and demoralize the remaining team. A thoughtful employee benefit package, even a modest one, signals that the company values its people and helps with retention.
Buy-Sell Funding: Keeping the Business in the Right Hands
A buy-sell agreement is a legal contract among business owners that dictates what happens to an ownership interest when a partner dies, becomes disabled, or wants to exit. The agreement sets a price or a formula for the buyout and specifies who can buy the interest. But a buy-sell agreement without funding is just a promise. Life insurance is the most common and reliable way to fund that promise, ensuring the surviving owners have cash exactly when they need it.
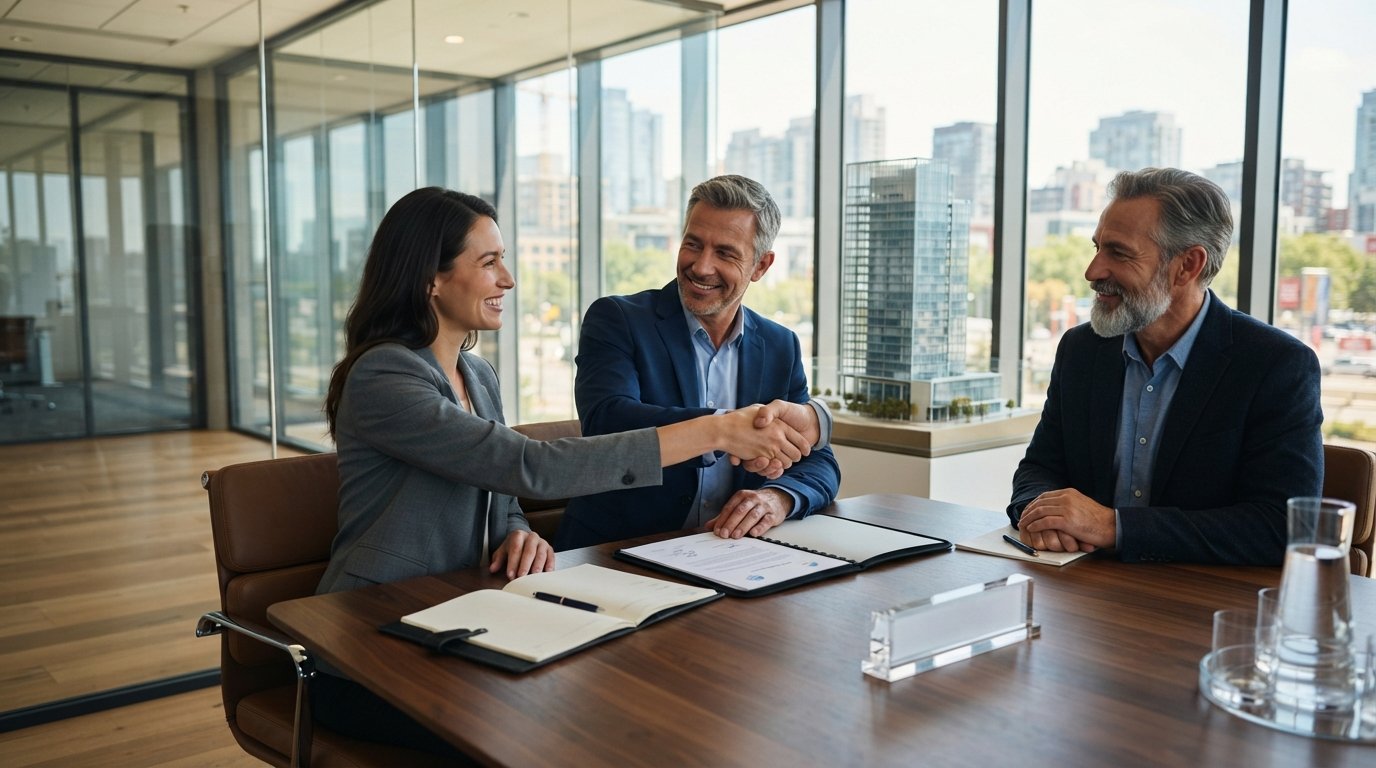
There are two main approaches to structuring the insurance. In a cross-purchase plan, each owner buys a policy on the life of every other owner. When one owner dies, the surviving owners receive the death benefit and use it to buy the deceased owner's shares from the heirs. This approach works well for a small number of owners, but it becomes administratively complex as the number of partners grows. In an entity-purchase plan, the business itself owns the policies and is the beneficiary. When a partner dies, the company receives the death benefit and uses it to redeem the deceased partner's shares. This keeps the ownership structure simpler, but the surviving owners should be aware that the death benefit may increase the value of their own shares, which can have tax implications.
Funding a buy-sell agreement with life insurance offers several concrete advantages. The death benefit is generally income-tax-free to the beneficiary, providing a pool of cash that is not dependent on the business's current cash flow. It also sets a predictable funding mechanism, reducing the risk of disputes among heirs and surviving owners. And because the policy is purchased while everyone is alive and insurable, it avoids the nightmare scenario of a partner becoming uninsurable later. Business owners should work with a qualified attorney and a licensed insurance professional to choose the right structure and to review the agreement regularly as ownership changes.
Key Person Coverage: Replacing What an Essential Employee Brings
Key person life insurance is a policy owned by the business on the life of an owner or a critical employee. The business is the beneficiary and pays the premiums. If the insured person dies, the company receives the death benefit, which can be used to cover the financial disruption caused by the loss. This coverage is not about replacing a person, which is impossible, but about buying the company time to recover, recruit, and stabilize.
The death benefit from a key person policy can replace several categories of financial loss. It can offset the cost of finding and training a replacement, which for specialized roles can be substantial. It can cover lost revenue or profits during the transition period. It can provide funds to reassure lenders and creditors that the business remains creditworthy. And it can help with the cost of recruiting and relocating a new executive. For many companies, the death benefit is designed to cover a multiple of the key person's compensation, often three to five times salary, though the right amount depends on the person's role and the company's financial exposure.
One often-overlooked benefit of key person coverage is its effect on employee confidence. When a company demonstrates that it has planned for the loss of a critical team member, it signals stability and professionalism to employees, customers, and partners. It also protects the owner's own family: if the owner is the key person, the policy can provide funds to keep the business running while the family decides whether to sell or continue.
Employee Group Life Benefits: A Safety Net That Also Attracts Talent
Group term life insurance is one of the most cost-effective benefits an employer can offer. It provides a death benefit to employees' beneficiaries, typically a multiple of salary, and often includes supplemental coverage that employees can purchase at their own expense. For many workers, group life is the only life insurance they have, making it a meaningful part of a total compensation package.
From the employer's perspective, group life insurance helps with recruitment and retention. In a competitive labor market, a solid benefits package can be the difference between hiring a top candidate and losing them to a competitor. It also supports morale and loyalty, because employees see that the company cares about their families' financial security. The cost is often predictable and can be partially or fully employer-paid, with options for employee-paid supplemental coverage.
It is important to understand how group life interacts with personal policies. Group coverage is typically tied to employment, so it ends when the employee leaves the company. It may also have limits, such as a cap on the death benefit or a reduction after a certain age. Employees who rely solely on group life may find themselves underinsured, especially if they have a mortgage, children, or other financial obligations. A personal term life policy can fill that gap, and it stays with the employee regardless of job changes. Business owners should encourage employees to review their personal coverage alongside their group benefits, and they can use a comparison tool to see how affordable individual term life can be.
Sizing Personal and Business Coverage Together
Business owners often wear two hats: they are both the owner of a company and a member of a household. The coverage strategy should reflect both roles. On the personal side, the owner needs enough life insurance to replace income, cover debts, fund education, and provide for a surviving spouse or dependents. On the business side, the owner needs coverage to fund buy-sell agreements, protect against key person loss, and potentially provide employee benefits. These needs are separate and should be addressed with separate policies or a coordinated plan.
A practical framework for sizing coverage starts with a personal needs analysis. Calculate the income replacement needed for the family, add outstanding debts (including mortgages and business loans that are personally guaranteed), and factor in future obligations like college tuition. Then, on the business side, determine the buy-sell funding requirement based on the value of each owner's stake, and assess the key person exposure for each critical employee. The two calculations should be done independently and then reviewed together to avoid gaps or overlaps.
For a more precise estimate, business owners can use a quote comparison service to see real numbers from multiple carriers. This is where a platform like USLifeQuote can help: it connects business owners with licensed agents who can analyze both personal and business needs and suggest affordable options. Comparing quotes from several carriers is essential because pricing varies significantly based on age, health, coverage amount, and policy type. A single conversation with a licensed agent can save hours of research and reveal options that are not obvious from a simple online search.
How to Choose the Right Policies and Partners
Selecting the right life insurance for business owners protecting partners and employees requires more than just picking a policy. It requires a coordinated team: an attorney to draft or review the buy-sell agreement, a CPA to understand the tax implications of ownership and beneficiary designations, and a licensed insurance professional to structure the policies correctly. The insurance agent should have experience with business-owned policies, as the tax rules and underwriting considerations can be different from personal coverage.
When evaluating carriers, look for financial strength ratings, a history of reliable claims payment, and competitive pricing for the specific type of coverage you need. Term life is often the most cost-effective choice for buy-sell funding and key person coverage because it provides a guaranteed death benefit for a set period at a lower premium. Permanent life insurance, such as whole life or universal life, may be appropriate for estate planning or for funding long-term obligations, but it costs more. Group life is typically term coverage and is priced separately.
Finally, review your coverage annually or whenever a major change occurs: a new partner, a significant increase in business value, a new key employee, or a change in personal financial obligations. Life changes fast, and a policy that was adequate three years ago may leave a gap today. Regular reviews keep the protection aligned with reality.
Proactive planning is the difference between a business that survives a crisis and one that becomes a cautionary tale. Whether you are funding a buy-sell agreement, protecting a key person, or offering employee benefits, the right life insurance strategy provides certainty and cash when it matters most. Start by understanding your risks, then use a trusted comparison service and a team of professionals to build a plan that protects everyone who depends on your business.