How to Lower Life Insurance Costs with Policy Review
A policy review can reveal savings on your life insurance. Call (833)-212-4240 to compare options and lower your costs without losing coverage.
By Lunara Voss
Your life insurance policy is not a set-and-forget product. The coverage you bought five or ten years ago may no longer match your life, and worse, it may be costing you more than necessary. A policy review is a structured look at your current coverage, your premium, and your needs, and it is one of the most effective ways to lower life insurance costs without sacrificing the protection your family relies on. Whether you have experienced a health improvement, welcomed a child, paid off a mortgage, or simply suspect that today's rates are more competitive, reviewing your policy can reveal savings you did not know existed. This guide walks you through how to lower life insurance costs with policy review, from timing the review to comparing fresh quotes and avoiding costly mistakes.
When a Policy Review Makes Sense After Health or Family Changes
A policy review is not just an annual chore; it is a strategic response to change. Certain life events create a clear signal that your existing coverage should be reexamined. If you have quit smoking, lost weight, or brought a chronic condition under control, your health profile may now qualify you for a lower rate class. Insurers price policies based on risk, and improved health can translate directly into premium savings. Similarly, if you have gotten married, divorced, had a child, or seen a child become financially independent, the amount of coverage you need may have shifted. A review helps you align your policy with your current responsibilities.
Family changes also include the death of a beneficiary, a change in guardianship, or a new special needs dependent. Each of these events affects how much coverage is appropriate and how it should be structured. For example, parents who originally bought a 30-year term policy to cover a newborn may now find that a shorter term or a different coverage amount is more efficient. On the other hand, a growing family or a new mortgage might mean you need more coverage, and a review can help you find affordable options without overpaying. The key is to treat a policy review as a proactive step, not a reaction to a crisis.
Another trigger is a change in your financial situation. If you have paid off high-interest debt, increased your savings, or built a larger emergency fund, you may be able to reduce your death benefit and lower your premium. Conversely, if you have taken on a business loan or co-signed a debt, you may need additional coverage. A review clarifies these trade-offs. It also gives you a chance to confirm that your beneficiary designations are up to date, which is essential for ensuring that the right people receive the proceeds. In short, any significant life event is a cue to sit down with your policy and ask whether it still fits.
Comparing Current Coverage with Today's Quotes
One of the most straightforward ways to lower life insurance costs with policy review is to compare your existing policy against fresh quotes. The insurance market is competitive, and rates change over time. A policy that was competitively priced a decade ago may now be above market. By requesting new quotes, you can see whether another carrier offers the same death benefit for a lower premium. This is not about chasing every slight difference; it is about identifying meaningful savings that make a switch worthwhile.
When comparing, look beyond the premium. Check the financial strength ratings of the insurer, the terms of the policy, and any riders or features you may lose by switching. For example, a convertible term policy may offer future flexibility that a cheaper policy lacks. Also consider the cost of a new medical exam and the time it takes to underwrite a new policy. If you are in good health, the savings can be substantial, but if you have new health issues, staying with your current policy may be the better choice. A side-by-side comparison helps you make an informed decision.
For a broader look at balancing cost and coverage, see our guide on affordable life insurance plans that cut costs without sacrificing the protection your family needs. It explains how to evaluate trade-offs and find a policy that fits your budget. When you are ready to see real numbers, you can also use a comparison platform to gather multiple quotes in one place. This is where a service like USLifeQuote can be helpful: it connects you with licensed agents who can analyze your needs and present competitive options from multiple carriers.
Reducing Coverage or Term Length in a Refi Scenario
If your goal is to lower your premium, one option is to reduce your coverage amount or shorten your term length. This is sometimes called a refi scenario, and it can make sense when your financial obligations have decreased. For instance, if your mortgage is nearly paid off and your children are adults, you may no longer need a $500,000 death benefit. Reducing the death benefit can lower your premium significantly. Similarly, if you originally bought a 30-year term but your need will end in 15 years, you may be able to buy a 15-year term at a lower rate.
However, reducing coverage is not without risks. You need to ensure that your beneficiaries would still be adequately protected. A good rule of thumb is to calculate your outstanding debts, future education costs, and income replacement needs before you cut your coverage. If you reduce too much, your family could face a financial shortfall. Also, if you shorten your term, you may lose the guaranteed renewability or conversion privileges of your original policy. Review the policy contract carefully and consider whether the savings justify the reduced protection.
Another refi strategy is to replace a whole life policy with a term policy. Whole life insurance builds cash value but comes with higher premiums. If your primary goal is to lower costs and you do not need the cash value component, switching to term could free up significant cash flow. Before you surrender a whole life policy, though, check for surrender charges and tax implications. A policy review can help you weigh the pros and cons and decide whether a refi makes sense for your situation. The key is to never reduce coverage without a clear plan for replacement if your needs change.
Risks of Dropping Coverage Without Replacement
One of the biggest mistakes people make when trying to lower life insurance costs is dropping their existing policy before securing a new one. This creates a dangerous coverage gap. If something happens during that gap, your family could be left without the financial protection they need. Worse, if your health has changed, you may not qualify for a new policy at all, leaving you uninsured. Always secure new coverage first and wait until it is in force before canceling your old policy.
Another risk is losing valuable features. Older policies may have guaranteed insurability, waiver of premium riders, or conversion options that are no longer available. If you drop the policy, you lose those benefits permanently. Additionally, some policies have surrender charges or loans that must be repaid. A policy review should include a careful reading of the contract to identify any hidden costs or lost benefits. If you are working with an agent, ask them to explain the consequences of dropping the policy in plain language.
Finally, consider the tax implications. Life insurance death benefits are generally tax-free, but if you surrender a cash value policy, you may owe taxes on the gain. If you take a loan against the policy, unpaid loans reduce the death benefit. These factors can erode the savings you hoped to achieve. The safest approach is to keep your current policy in place until a replacement is fully approved and you have confirmed that the new policy meets your needs. A thorough review helps you avoid these pitfalls.
Steps to Request a Fresh Quote and Compare
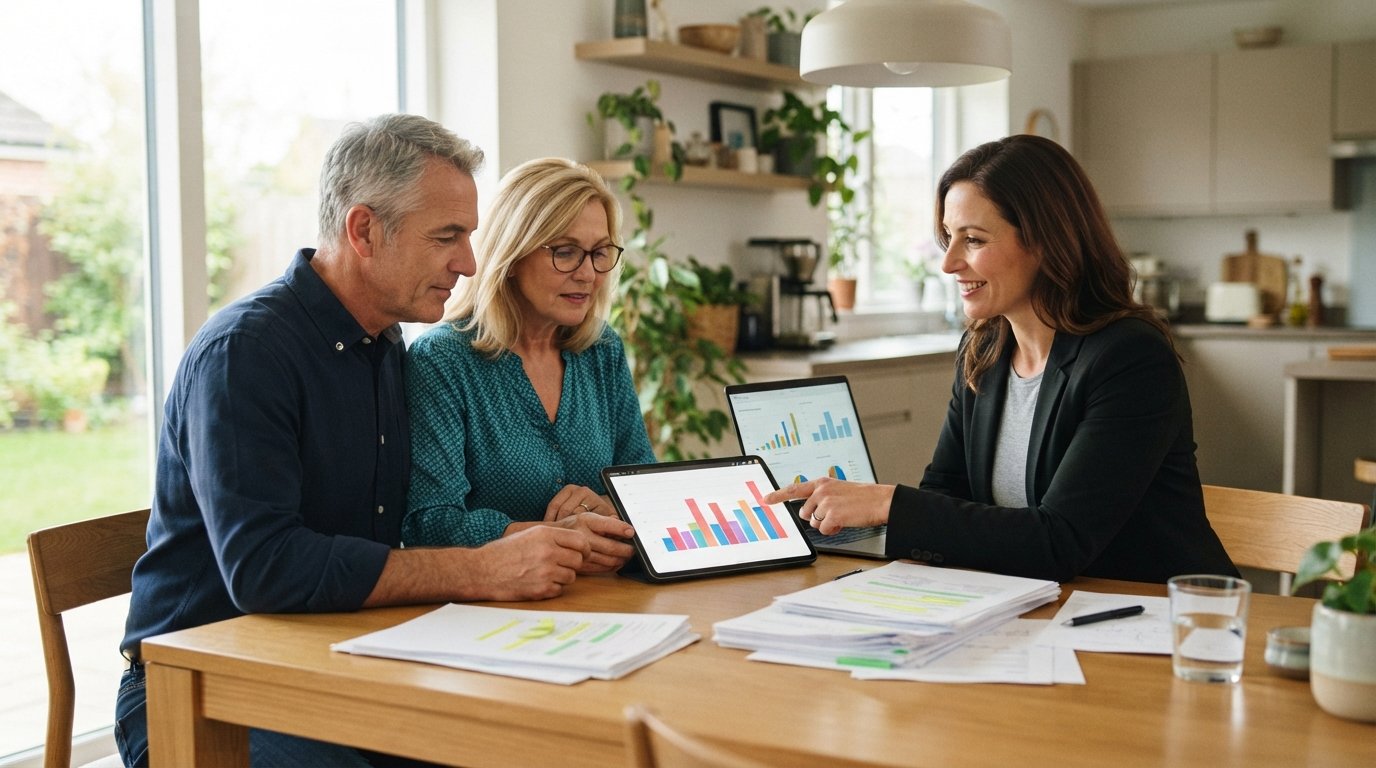
Ready to take action? Follow these steps to request a fresh quote and compare it with your current policy. First, gather your current policy documents, including the declarations page, premium schedule, and any riders. Note the death benefit, term length, premium, and cash value (if any). Second, assess your current needs using a needs calculator or a conversation with a financial professional. Consider your debts, income replacement, education costs, and final expenses. Third, request quotes from multiple carriers. You can do this through an independent agent or a comparison platform. Be prepared to provide health and lifestyle information.
Here is a simple checklist to guide the comparison process:
- List your current premium and coverage details.
- Obtain at least three quotes for the same or similar coverage.
- Compare not just the premium but also the insurer's financial strength and policy features.
- Check the underwriting requirements and estimated time to approval.
- Review the fine print for exclusions, riders, and conversion options.
After you have the quotes, compare them side by side. Look for the best combination of price and protection. If you find a lower premium, confirm that the new policy will be in force before you cancel the old one. Also, consider whether you can negotiate with your current insurer; sometimes they will offer a better rate or a policy change to keep your business. If you are working with an agent, ask for a formal policy review and a written comparison. This documentation helps you make a confident decision.
Remember that lowering your life insurance costs is not just about finding the cheapest premium. It is about maintaining adequate coverage for your family while freeing up money for other goals. A policy review is an opportunity to align your coverage with your current life and to ensure that you are not overpaying. Whether you are in your 30s with young children or in your 60s with grown children, a periodic review can uncover savings and peace of mind. Take the time to review your policy today, and if you need help, reach out to a licensed professional who can guide you through the process.