How Occupation and Hobbies Change Life Insurance Premiums
Occupation and hobbies change life insurance premiums more than you think. Get an accurate quote by calling (833)-212-4240 and avoid surprises.
By Lunara Voss
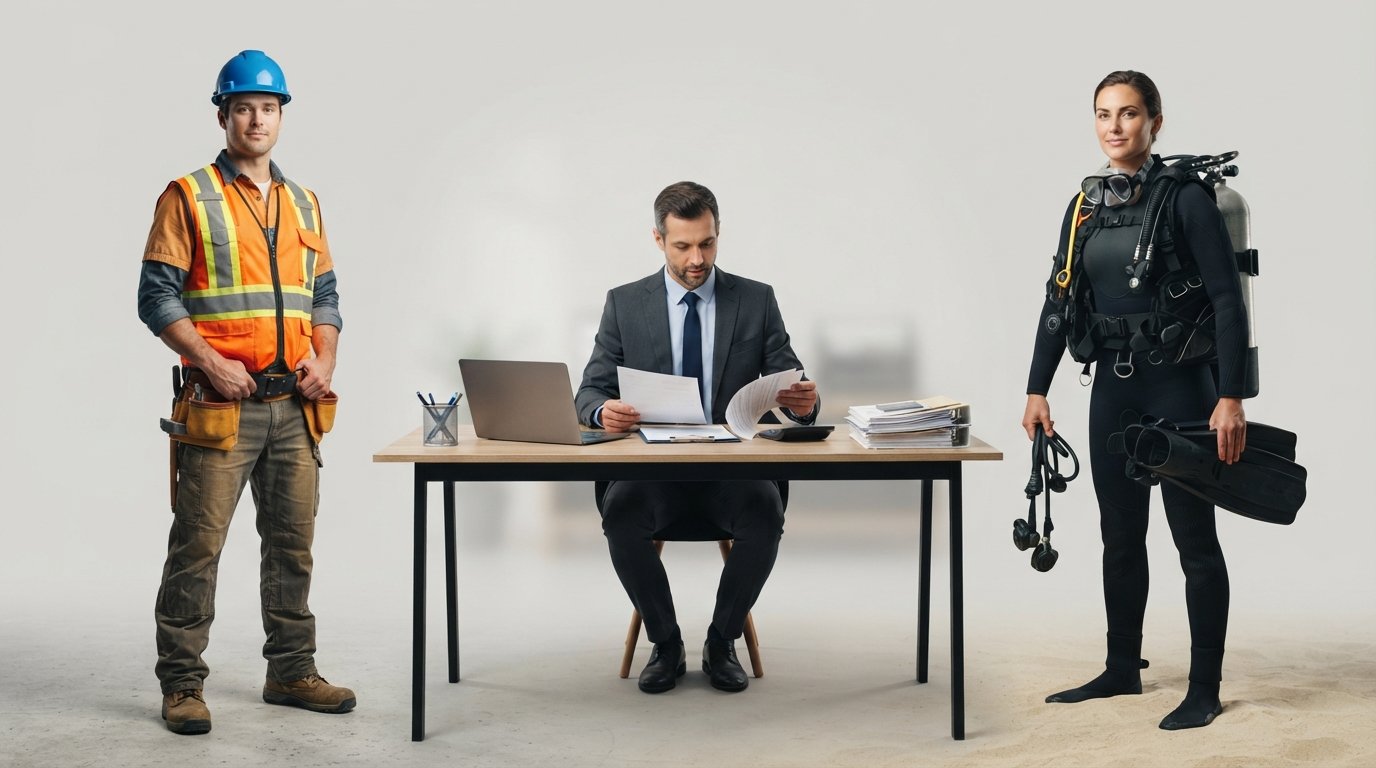
Your job title and weekend plans might cost you more than you think. When you apply for life insurance, underwriters do not just look at your age and health. They also assess how you spend your working hours and your free time. That is why two people of the same age and health can receive very different quotes. Understanding how occupation and hobbies change life insurance premiums can help you avoid surprises, plan ahead, and possibly save money. Whether you are a nurse, a scuba diver, or a weekend racer, your lifestyle leaves a financial footprint on your policy.
Why Insurers Care About Your Job and Pastimes
Life insurance is priced on risk. Insurers want to know the likelihood that they will have to pay a claim sooner rather than later. Certain occupations and hobbies carry higher risks of injury or death, which raises the chance of an early claim. To compensate, insurers charge higher premiums or apply exclusions. The classification process is not arbitrary: it is based on actuarial data that links specific activities to mortality and morbidity rates. Even if you are healthy, the nature of your work or leisure can push you into a higher risk class.
Many applicants are surprised to learn that their profession alone can add hundreds of dollars to an annual premium. For example, a construction worker may pay more than an office manager of the same age. Similarly, a hobby like rock climbing can trigger a rating adjustment. The key is transparency: hiding risky activities can lead to a denied claim. By understanding how occupation and hobbies change life insurance premiums, you can accurately present your situation and find coverage that fits.
Occupational Risk Classes: How Your Job Is Rated
Insurers typically use a classification system that groups occupations into risk categories. These classes range from preferred (low risk) to substandard (high risk). The classification is based on factors such as workplace hazards, physical demands, and potential for accidents. For instance, a software engineer falls into a preferred class, while a roofer might be rated as substandard. Some insurers use a 1-4 or A-F scale, but the principle is the same: the higher the risk, the higher the premium.
Certain occupations are commonly rated as higher risk. These include:
- Construction and industrial trades (e.g., welders, electricians, crane operators)
- Emergency responders (firefighters, police officers, paramedics)
- Transportation and logistics (truck drivers, airline pilots, delivery drivers)
- Agricultural and fishing workers
- Mining and extraction workers
However, not all high-risk jobs are treated equally. An underwriter will consider your specific duties. For example, a police officer in a desk job may be rated differently from a patrol officer. Similarly, a construction manager who rarely visits sites might qualify for a better rate than a laborer. When you request quotes, provide accurate details about your role to avoid misclassification.
If your occupation is considered high risk, you may still find affordable coverage. Some insurers specialize in high-risk occupations, and a broker can help you compare options. Using a platform like LifeAgency can connect you with agents who understand occupational ratings. Additionally, our guide on finding the best life insurance brokers can help you navigate the process.
Hobbies That Can Raise Your Premium
Your leisure activities matter just as much as your job. Insurers classify hobbies into risk categories, and some can significantly increase your premium. Aviation, scuba diving, rock climbing, and auto racing are among the most common high-risk hobbies. Each carries its own set of underwriting guidelines.
Aviation
If you are a private pilot, your life insurance premium may increase. Insurers will want to know your flight hours, type of aircraft, and whether you fly for pleasure or business. Some policies exclude aviation-related deaths entirely, while others offer coverage with a rider for an additional cost. If you are a student pilot, you may face stricter underwriting until you have logged more hours.
Scuba Diving
Scuba diving is often rated as a higher-risk hobby, especially if you dive deep or frequently. Insurers may ask about your certification level, maximum depth, and number of dives per year. Recreational divers who stay within safe limits may qualify for standard rates, while technical divers or those who dive in caves may face exclusions or higher premiums.
Climbing and Mountaineering
Rock climbing, ice climbing, and mountaineering are considered hazardous activities. The risk depends on the type of climbing (e.g., sport climbing vs. free soloing), frequency, and location. Insurers may exclude climbing-related deaths or charge an extra premium. If you climb occasionally and use proper safety gear, you may still find affordable coverage.
Auto Racing
Auto racing, including drag racing and motorcycle racing, is a high-risk hobby that can lead to a substandard rating. Some insurers will not cover professional racers at all. If you race as a hobby, you may need a specialized policy or a rider. Be prepared to provide details about the type of racing, frequency, and safety record.
For other hobbies, such as skiing, snowboarding, or boating, the impact on your premium is usually less severe. However, it is always best to disclose all activities to your agent. If you are unsure how a hobby affects your rate, ask for a pre-qualification with several insurers.
When a Rider or Exclusion Applies
For high-risk occupations and hobbies, insurers often use riders or exclusions to manage risk. A rider is an add-on that provides coverage for a specific activity, usually for an extra premium. An exclusion, on the other hand, means the policy will not pay out if death occurs while engaging in that activity. For example, a policy might exclude death during scuba diving unless you purchase a rider.
It is crucial to understand the terms of your policy. If you participate in a high-risk hobby, an exclusion could leave your beneficiaries without coverage. Always ask your agent whether a rider is available and compare the cost. In some cases, it may be more affordable to choose a policy with an exclusion and purchase separate accident coverage.
How to Request a Reconsideration for a Hobby Rating
If you feel that your hobby has been unfairly classified, you can request a reconsideration. Insurers sometimes use broad categories that do not accurately reflect your actual risk. For instance, if you are a recreational scuba diver who only dives in shallow waters, you may be able to provide evidence to support a lower rating. Here are steps to request a reconsideration:
- Gather documentation: Collect proof of your experience, certifications, safety records, and frequency of participation.
- Contact your agent or insurer: Explain your situation and provide the evidence.
- Ask for a reclassification: Request that the underwriter review your case with the new information.
- Consider a different insurer: If the first insurer does not budge, shop around. Some insurers are more lenient with certain hobbies.
Keep in mind that underwriters have the final say, but providing accurate and detailed information can work in your favor. It also helps to work with an agent who specializes in high-risk cases. They know which insurers are more likely to offer favorable terms.
Comparing Quotes with Accurate Occupation Data
To avoid surprises later, always provide accurate information about your occupation and hobbies when requesting quotes. If you underestimate your risk, the insurer may later rescind the policy or deny a claim. That is why it is essential to be honest from the start. When you use a quote comparison service, you can see how different insurers rate your specific situation.
At LifeInsurance-Quote.com, we connect you with licensed agents who can help you compare quotes from multiple carriers. Our platform is free and has no obligation. You can enter your ZIP code, age, and tobacco use to get started. For high-risk occupations or hobbies, our agents can guide you through the underwriting process and help you find the best possible rate. Call us at (833)-212-4240 to speak with a professional.
Remember that life insurance is a long-term contract. By understanding how occupation and hobbies change life insurance premiums, you can make informed decisions and protect your family's financial future. Do not let a high-risk job or hobby deter you from getting coverage. With the right approach, you can find a policy that fits your needs and your budget.