How Life Insurance Premiums Change When You Quit Smoking
Quitting smoking can cut life insurance premiums by 30-50 percent, but insurers require 12-24 months of abstinence. Call (833)-212-4240 for expert guidance.
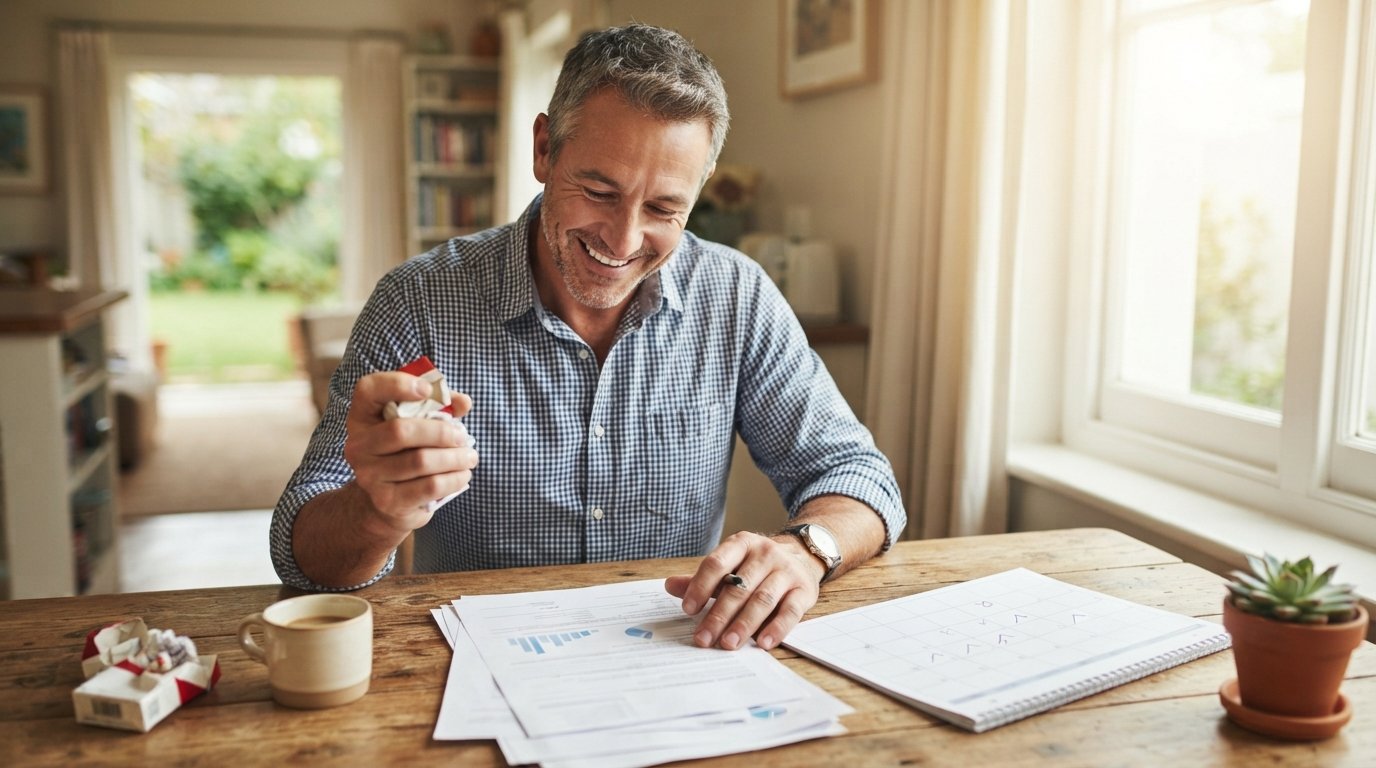
Your last cigarette may be behind you, but the financial hangover of tobacco use can linger on your life insurance policy for months or even years. If you recently quit smoking, you are probably wondering how life insurance premiums change when you quit smoking, and whether your current rate will ever reflect your healthier lifestyle. The short answer is yes, but the timeline and the savings depend on a mix of underwriting rules, verification methods, and how you approach your insurer. Understanding this process can put hundreds or even thousands of dollars back in your pocket each year.
The Real Rate Gap Between Smokers and Non-Smokers
Life insurance companies classify applicants into risk categories, and tobacco use is one of the most heavily weighted factors in that decision. A smoker can expect to pay roughly two to three times more for the same coverage compared to a non-smoker of the same age and health profile. For a 40-year-old male seeking a 20-year, $500,000 term policy, a non-smoker might pay around $30 per month, while a smoker could pay $75 to $100 or more. Over the life of the policy, that gap can add up to tens of thousands of dollars.
The reason is straightforward: tobacco use is linked to a long list of serious health conditions, including cancer, heart disease, and respiratory illness. Insurers price that elevated risk into your premium. The moment you quit, your risk profile begins to improve, but insurance underwriting moves slower than your body does. Most carriers want to see a sustained period of abstinence before they will reclassify you.
It is also worth noting that the rate gap varies by carrier and product type. Term life insurance tends to show the most dramatic difference because the policy period is shorter and the risk is concentrated. Permanent policies like whole life or universal life may also adjust, but the savings can be less pronounced because the cash value component and longer duration change the math. If you are comparing options, our guide on affordable life insurance plans explains how to cut costs without sacrificing coverage.
Typical Waiting Periods Before Non-Smoker Rates Apply
One of the most common frustrations for recent quitters is discovering that their new smoke-free status does not automatically translate into a lower premium. Insurers generally require a waiting period, typically 12 months of complete nicotine abstinence, before they will consider you for non-smoker rates. Some carriers extend that period to 24 months or even 36 months for applicants with a long history of heavy smoking or related health issues.
The waiting period exists because relapse rates are high in the first year, and insurers want to see a genuine lifestyle change before they adjust your risk classification. During this period, your policy remains in the smoker category, and you will continue to pay the higher premium. However, the clock starts on your quit date, not on the date you inform your insurer. Documenting your quit date with a medical professional or a cessation program can help you prove your abstinence when the time comes.
Here is a general timeline you can expect after quitting smoking:
- 0 to 12 months: You remain in the smoker or tobacco-user category. Premiums stay at the higher rate.
- 12 to 24 months: Many carriers will now consider you for non-smoker rates, often requiring a nicotine test and a health questionnaire.
- 24 to 36 months: Some carriers, especially those with stricter underwriting, may require this longer period before reclassification.
- 36 months and beyond: You are generally eligible for the best non-smoker rates, assuming all other health factors are favorable.
These timelines are not universal, and they can vary based on the carrier, the policy type, and your overall health profile. The key takeaway is that quitting is a long-term investment in your insurance costs, not an overnight fix.
How Underwriting Verifies Tobacco and Nicotine Use
Insurance companies do not simply take your word for it when you say you have quit. They have several tools to verify nicotine use, and misrepresenting your status can have serious consequences, including policy rescission or denied claims. The most common verification method is a nicotine test, typically a urine or saliva test, administered during the underwriting process. These tests can detect cotinine, a metabolite of nicotine, for up to several days or even weeks after your last use.
In addition to lab tests, underwriters may review your medical records for any mention of tobacco use, prescriptions for cessation aids, or notes from your doctor. They may also ask detailed questions about your quit date, the methods you used, and whether you have had any slips. Some carriers use prescription databases to check for nicotine replacement therapies, though using these aids is generally acceptable as long as you are not actively using tobacco.
It is important to be honest throughout the process. If you quit and then relapse, even for a single cigarette, you should disclose it. Insurers understand that quitting is difficult, but they need accurate information to assess risk. If you are unsure about how to present your history, working with a licensed agent can help you navigate the underwriting process and avoid costly mistakes. Platforms like USLifeQuote connect you with agents who can guide you through the nuances of tobacco underwriting.
Reapplying or Requesting a Rate Review After Quitting
Once you have met the waiting period, you have two main paths to lower your premium: requesting a rate review on your existing policy or reapplying for a new policy. A rate review, sometimes called a reconsideration, involves asking your current insurer to reclassify you based on your new tobacco-free status. Not all carriers allow this, and those that do may require a new medical exam or at least a nicotine test. The advantage is that you keep your existing policy and its benefits, and you avoid the hassle of a new application.
Reapplying for a new policy means going through the full underwriting process again. This can be beneficial if your health has improved in other ways, or if you can find a carrier with more favorable rates for former smokers. However, it also means a new contestability period and potentially new medical exams. If your health has changed for the worse since your original policy, you might be better off staying with your current insurer and requesting a review.
Here is a step-by-step approach to get your premium adjusted:
- Confirm your quit date and gather documentation. Keep records of your quit date, any cessation programs, and doctor visits that note your tobacco-free status.
- Contact your insurer or agent. Ask about their specific policy for reclassification and what evidence they require.
- Complete any required tests. This may include a nicotine test, a medical exam, or a health questionnaire.
- Compare new quotes. If your current insurer is not competitive, use a quote comparison service to see what other carriers offer for former smokers.
- Decide whether to stay or switch. Weigh the savings against the hassle of a new application and any new contestability period.
The cost savings from reclassification can be substantial. Even a modest reduction in premium adds up over the years, and the earlier you start the process, the sooner you can benefit. Do not wait until your policy renews; proactive requests often yield faster results.
Other Lifestyle Changes That May Lower Premiums
Quitting smoking is one of the most impactful changes you can make for your life insurance premiums, but it is not the only one. Insurers also reward other healthy behaviors and improvements in your health profile. Losing excess weight, lowering your blood pressure, and improving your cholesterol can all move you into a more favorable risk category. Even small changes, like exercising regularly and maintaining a healthy diet, can be reflected in your underwriting results over time.
If you have other health conditions, such as diabetes or sleep apnea, managing them effectively and documenting your progress can also help. Some carriers offer preferred rates for applicants who demonstrate consistent management of chronic conditions. Additionally, avoiding risky hobbies (like skydiving or scuba diving) and maintaining a clean driving record can positively influence your premium. When you reapply or request a review, be prepared to provide evidence of these improvements, such as recent lab results or a letter from your doctor.
It is also worth considering the timing of your application. If you are close to a milestone, such as a one-year anniversary of quitting or a significant weight loss goal, waiting a few weeks or months could result in a better rate class. A licensed agent can help you time your application strategically to maximize savings.
Frequently Asked Questions
Can I get non-smoker rates immediately after quitting?
In most cases, no. Insurers typically require at least 12 months of nicotine abstinence before considering you for non-smoker rates. Some carriers may require 24 months or more. It is best to check with your specific insurer or work with an agent who knows the underwriting guidelines of different carriers.
What if I use nicotine replacement therapy like gum or patches?
Using nicotine replacement therapy (NRT) is generally acceptable as long as you are not using tobacco products. However, some carriers may still classify you as a nicotine user while you are using NRT. Be sure to disclose your use and ask how the carrier treats NRT in their underwriting guidelines.
Will my premium automatically go down after the waiting period?
No, your premium will not automatically decrease. You must request a rate review or reapply for a new policy. Insurers do not proactively lower premiums without an application or request from the policyholder.
Can I be denied coverage if I admit to a relapse?
A single relapse does not automatically lead to denial, but it may reset your quit clock. Insurers want to see sustained abstinence. If you relapse, it is best to be honest and wait until you have met the required abstinence period before applying or requesting a review.
How much can I save by quitting smoking?
Savings vary widely based on age, health, coverage amount, and policy type. On average, former smokers can save 30 to 50 percent on their premiums compared to smoker rates. For a $500,000 term policy, that could mean thousands of dollars per year.
Quitting smoking is one of the best financial decisions you can make for your life insurance costs. While the savings are not immediate, they are substantial and well worth the wait. By understanding the waiting periods, verification methods, and options for reclassification, you can take control of your premiums and secure affordable coverage for your family. If you are ready to explore your options, request a quote today and see how much you could save as a former smoker.