How Health Impacts Life Insurance Premiums: A 2026 Guide
Your health profile directly shapes life insurance rates. Learn which factors matter most and how to compare quotes accurately. Call (833)-212-4240 for guidance.
By Tarian Vex
Your health is the single most powerful lever on what you pay for life insurance. Two people the same age requesting the same coverage amount can receive quotes that differ by hundreds of dollars a year, simply because one has well-controlled blood pressure and the other has an elevated reading on record. Insurers are not trying to penalize you; they are pricing risk. The more predictable your health profile looks on paper, the less they charge for the promise to pay your beneficiaries. Understanding how health impacts life insurance premiums before you request quotes puts you in a stronger negotiating position and helps you avoid comparing apples to oranges.
The Health Factors Underwriters Weigh Most Heavily
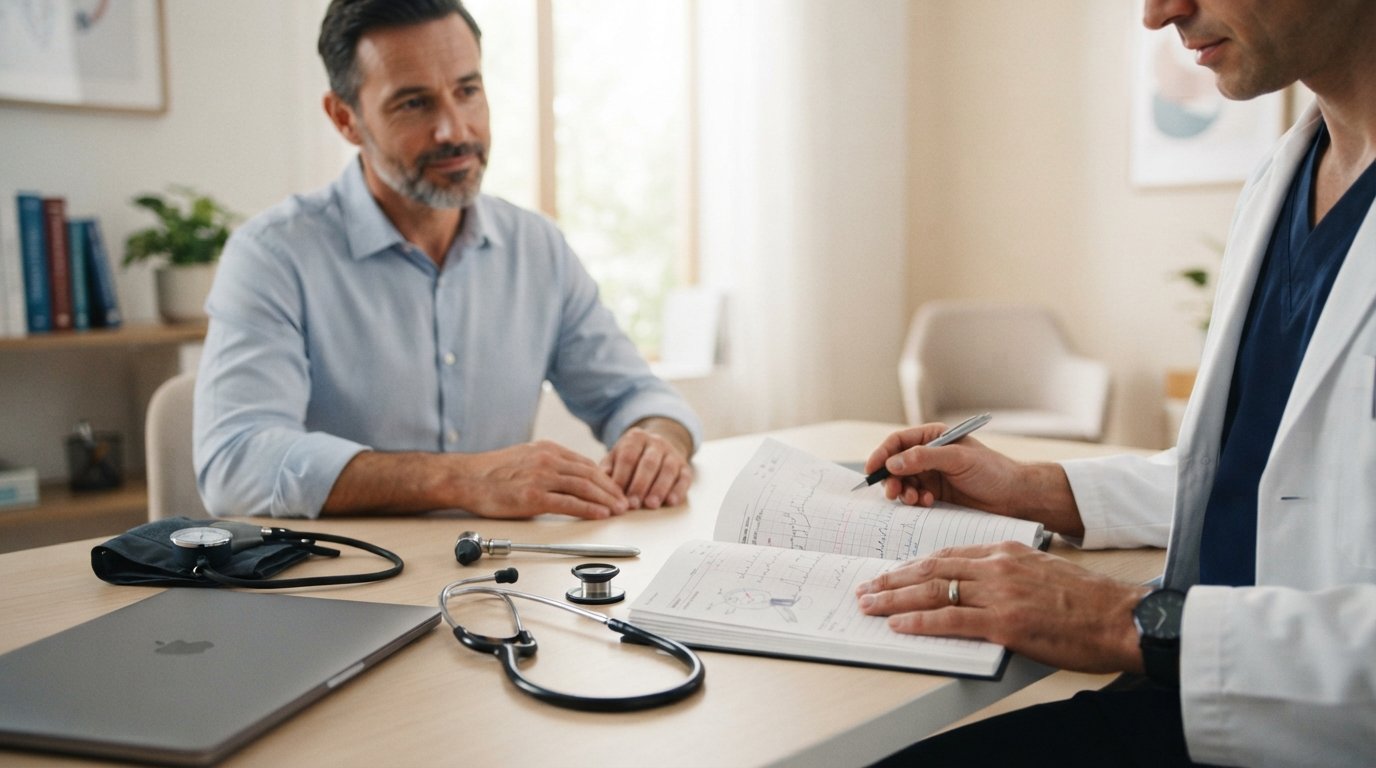
When you apply for traditional fully underwritten coverage, the insurer builds a risk profile from your application, your medical records, and often a paramedical exam that includes bloodwork and a physical measurement. Certain readings carry outsized weight because they correlate strongly with mortality risk over the policy term. Blood pressure, cholesterol, and body mass index (BMI) sit at the top of that list, followed closely by markers of metabolic health such as blood glucose and liver enzymes.
Blood pressure is a classic example. A reading of 120/80 or lower typically keeps you in a preferred tier. Once readings climb into the 140s over 90s, or if you take multiple medications to control hypertension, carriers may move you into a standard or substandard class. Cholesterol works similarly: total cholesterol, LDL, HDL, and the ratio between them all matter, and well-managed levels with or without medication can still earn favorable treatment at many carriers. BMI is trickier because it is a blunt instrument. Carriers often pair your height and weight with a build chart, and they may credit you for athletic build or penalize you for central obesity even when your BMI looks acceptable.
Bloodwork tells the deeper story. A comprehensive metabolic panel can reveal early kidney or liver strain, while a complete blood count flags anemia or other conditions. Carriers also screen for cotinine (a nicotine byproduct), HIV, and sometimes prostate-specific antigen or other markers depending on age and gender. If any of these readings fall outside preferred ranges, the underwriter may order additional tests or attach a rating that increases your premium. The key takeaway is that these are not pass-fail tests; they are inputs into a risk score, and small improvements before you apply can move you into a better tier.
Build, Family History, and Driving Record: The Hidden Premium Levers
Beyond the lab results, three factors quietly shape your premium tier: your build, your family medical history, and your driving record. Build is more than a number on a scale. Underwriters look at your weight relative to height, your age, and sometimes your waist circumference. A muscular applicant with a high BMI may be treated more favorably than a sedentary applicant with the same BMI, but you usually need to document that through a physical exam or a note from your physician. If you are close to a build chart threshold, losing even a few pounds before the exam can sometimes shift you into a lower-priced class.
Family history matters most for applicants with a parent or sibling who developed heart disease, stroke, or certain cancers before age 60. Carriers may add a modest rating or simply require you to be in a standard class rather than preferred. The impact varies widely by carrier: some are aggressive about family history, while others treat it as a minor adjustment. This is one of the clearest examples of why shopping multiple quotes matters. A profile that earns a preferred-plus offer at one company might receive a standard offer at another, and the difference in premium can be substantial over a 20- or 30-year term.
Driving record is the third hidden lever. Multiple moving violations, a DUI, or a license suspension in the past few years can push you into a higher risk class even if your health is excellent. Carriers view reckless driving as a behavioral risk indicator, and some will decline applicants with recent DUIs outright. If your record is clean, you gain an advantage that is easy to overlook. If it is not, waiting until older violations age off your record (typically three to five years) can meaningfully reduce your premium.
How Tobacco and Nicotine Use Are Defined (It Is Broader Than You Think)
Nicotine use is one of the most expensive health factors in life insurance. Smokers and vapers typically pay two to three times more than non-users for the same coverage, and the definition of "smoker" is broader than many shoppers expect. It includes cigarettes, cigars, pipes, chewing tobacco, snuff, nicotine patches, gum, and e-cigarettes or vaping devices. Even if you use nicotine occasionally, such as a cigar on weekends or a vape pen at social events, most carriers will classify you as a tobacco user unless you can document complete cessation for a required period.
Cessation timelines vary by carrier, but a common standard is 12 months of complete abstinence from all nicotine products before you can qualify for non-tobacco rates. Some carriers accept 24 months, and a few are more lenient for cigars or chewing tobacco than for cigarettes. The insurer will typically verify through a cotinine test during the paramedical exam, so disclosing use honestly is essential. If you quit recently, waiting until you cross the carrier's threshold can save you thousands of dollars over the life of the policy. In the meantime, you can still secure coverage at smoker rates and potentially reapply or request a reconsideration later.
It is also worth noting that carriers treat marijuana use differently than tobacco. Many now treat occasional marijuana use as non-smoker status, but daily use or vaping marijuana may still trigger tobacco rates at some companies. Because policies vary so much, the smartest approach is to disclose your actual usage pattern and let multiple carriers compete for your business.
Preparing Your Health Profile Before You Request Quotes
The quality of your quotes depends on the accuracy of the information you provide. If you understate your weight or omit a medication, the final offer after underwriting will be higher than the quote you used for comparison, which defeats the purpose of shopping. Before you request quotes, gather your recent medical records, know your current medications and dosages, and get a recent physical if you have not had one in the past year. This preparation helps you present a complete and accurate picture, and it also gives you a chance to address any correctable issues before the formal application.
Here is a practical sequence for preparing your health profile so your comparisons are reliable:
- Pull your numbers. Get your most recent blood pressure, cholesterol panel, and blood glucose readings from your doctor. If they are borderline, ask what a realistic target looks like before you apply.
- List every medication and supplement. Underwriters care about what you take, not just why. Include prescriptions, over-the-counter drugs, and herbal supplements, because some can affect lab results.
- Document your family history. Note the age and cause of death or diagnosis for parents and siblings. This helps you and your agent anticipate how different carriers will view your profile.
- Check your driving record. Request a copy of your motor vehicle report so you know what carriers will see before they see it.
- Consider timing. If you are close to a build chart threshold or a nicotine cessation milestone, waiting a few weeks or months can move you into a better rate class.
Once your profile is organized, you can compare quotes with confidence. This is also where working with a knowledgeable broker pays off. If you want to find the best life insurance brokers near you, look for professionals who can explain which carriers are most favorable for your specific health profile rather than simply quoting the first option available. A broker who understands underwriting niches can often place a borderline case with a carrier that views it favorably, saving you money without any change in your health.
Why the Same Health Profile Gets Different Rates at Different Carriers
Insurance companies are not identical in their underwriting. Each carrier has its own actuarial tables, its own appetite for certain conditions, and its own definition of preferred risk. One company may be lenient on controlled diabetes while another is strict; one may ignore a single elevated liver enzyme while another orders a full workup. This is not a flaw in the system; it is a feature of a competitive market. For you as a shopper, it means that requesting a single quote tells you very little about what you could actually pay.
The solution is to test multiple quotes with the same accurate health information. When you use a comparison platform, you can see how different carriers respond to your profile and identify the one that treats your specific situation most favorably. For example, an applicant with well-controlled hypertension and a family history of heart disease might see offers ranging from standard to preferred at different companies. The difference in monthly premium could be 20 to 40 percent, which adds up to thousands of dollars over a 20-year term. Testing multiple quotes is not about finding the absolute cheapest headline rate; it is about finding the carrier whose underwriting guidelines align with your actual health profile.
This is also why simplified-issue policies deserve a mention. If your health profile includes a condition that would trigger a decline or a heavy rating at fully underwritten carriers, a simplified-issue policy with no medical exam may be the only path to coverage. These policies ask health questions but skip the paramedical exam, and they can be issued quickly. The trade-off is a higher premium per thousand dollars of coverage and a lower maximum face amount. For some applicants, that is a worthwhile trade; for others, it makes sense to apply with a traditional carrier first and keep simplified issue as a fallback. The right choice depends on your specific health factors and how much coverage you need.
Finally, remember that you are not locked into a bad rate forever. Many carriers allow you to request a reconsideration if your health improves, such as after losing weight, quitting nicotine, or getting a condition under control. Some will reunderwrite your policy after a set period. If you are proactive about your health, you may be able to convert a substandard rating into a standard or preferred one within a few years. That possibility is one more reason to secure coverage now rather than waiting for perfect health, because the protection matters more than the perfect price.
When you are ready to see how your health profile translates into real quotes, you can compare personalized life insurance quotes from multiple carriers in one place. The process is free, there is no obligation, and it gives you the information you need to make an informed decision about protecting your family.
Health and life insurance premiums are tightly linked, but the link is not a mystery. By understanding which factors underwriters weigh, preparing your profile accurately, and testing multiple carriers, you can take control of the process and find coverage that fits both your health and your budget.