Denied Life Insurance? Steps to Take Next
Denied life insurance coverage? Get expert guidance on next steps and alternatives. Call (833)-212-4240 to explore your options today.
By Lucan Nyro
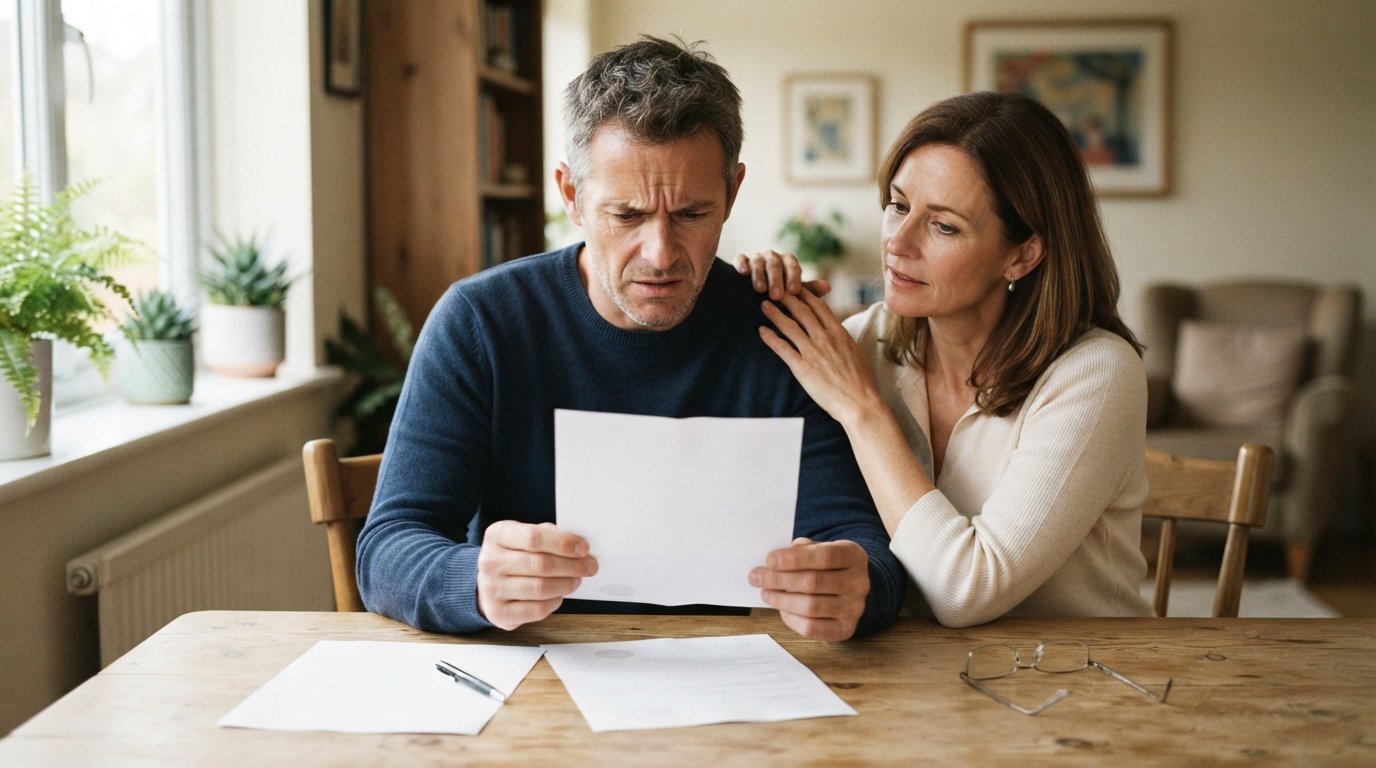
Receiving a denial letter for life insurance can feel like a door slamming shut, especially when you are trying to protect your family. But a decline is not the end of the road. It is a signal to pause, understand why it happened, and chart a new course. Thousands of people are declined each year, and many of them still find coverage through alternative paths. The key is to act methodically: read the letter carefully, ask for the specific reason, and explore every option before assuming you are uninsurable.
Start by Reading the Decline Letter and Requesting the Reason
The first step after a denial is to read the letter thoroughly. Insurers are required to provide a reason for adverse action, though the language can be vague. Look for phrases like "based on your medical records" or "due to your prescription history." This is your starting point. If the letter does not specify the exact condition or factor, you have the right to request a more detailed explanation. Under the Fair Credit Reporting Act, you can also request the consumer report the insurer used, which may contain errors.
Requesting the reason in writing serves two purposes. First, it helps you understand whether the denial was due to a temporary issue (like a recent hospitalization) or a chronic condition. Second, it gives you concrete information to share with an independent agent who can shop your case to multiple carriers. Do not accept a verbal explanation alone; ask for documentation you can keep.
Once you have the reason, categorize it. Was it a medical condition, a medication, a risky hobby, a driving record, or something else? This categorization will guide your next steps. For example, if the denial was due to high blood pressure that is now controlled, you may be able to reapply after a waiting period. If it was due to a history of cancer, you may need to wait until you are in remission for a certain number of years. Understanding the specific issue lets you address it head-on.
Explore Simplified Issue and Guaranteed Issue Alternatives
If a fully underwritten policy is out of reach, simplified issue and guaranteed issue policies are worth considering. Simplified issue policies ask a few health questions but do not require a medical exam. They are faster to process and often available for people with manageable health conditions. Guaranteed issue policies, on the other hand, accept everyone regardless of health, but they come with higher premiums and lower coverage amounts, typically capped at $25,000 or $50,000.
These alternatives can be a lifeline for those who need coverage quickly or who have been declined for traditional policies. However, it is important to understand their trade-offs. Simplified issue policies may still decline you based on your answers, so it is not a guarantee. Guaranteed issue policies often have a graded death benefit, meaning the full benefit is not paid out if you die within the first two or three years. Despite these limitations, they can provide peace of mind and cover final expenses.
When considering these options, work with an agent who specializes in impaired risk. They can help you compare simplified issue carriers that are more lenient with specific conditions. For instance, some carriers may accept you if your diabetes is well-controlled, while others may not. The same goes for heart disease, depression, and other common issues. A knowledgeable agent can save you time and prevent multiple declined applications, which can hurt your chances further.
Improve Health Factors Before Reapplying
If your denial was due to a health factor that can be improved, take steps to address it before reapplying. Insurers look at your overall health picture, including lab results, blood pressure, weight, and lifestyle habits. Small improvements can make a big difference. For example, lowering your blood pressure or losing weight can move you from a declined status to a rated policy with a higher premium. Quitting smoking, even for a short period, can also improve your chances, though most carriers require at least 12 months of abstinence to consider you a non-smoker.
Before reapplying, gather updated medical records and lab results that show improvement. Ask your doctor for a letter explaining any changes in your condition. This documentation can support your case and demonstrate that you are actively managing your health. Keep in mind that insurers may still decline you if the underlying condition is considered high-risk, but showing progress can sometimes lead to a more favorable outcome.
It is also wise to wait if your denial was due to a temporary issue, such as a recent surgery or a pending medical test. Many insurers require a waiting period of six months to a year after certain events. Reapplying too soon can result in another denial and further discourage you. Use the waiting time to build a healthier profile and consult with an agent about the best timing.
Work with an Agent to Target Lenient Underwriting Carriers
Not all insurance companies have the same underwriting guidelines. Some are more lenient with certain conditions, and an experienced independent agent knows which carriers to approach. Instead of applying blindly to multiple companies (which can lead to multiple denials), work with an agent who can match your profile to the right carrier. They can also help you prepare a cover letter explaining any special circumstances and advocate on your behalf.
When you speak with an agent, be honest and thorough about your health history. Withholding information can lead to a denial or even a rescinded policy later. Provide all requested documents and be prepared to discuss your medical records. The agent will use this information to pre-screen you with carriers before submitting a formal application. This pre-screening process can save you from unnecessary denials and help you find a policy that fits your needs and budget.
If you are looking for a starting point, consider using a platform that connects you with licensed agents who specialize in high-risk cases. For example, LifeAgency offers access to agents who can analyze your situation and suggest the best life insurance plan at an affordable cost. These professionals understand the nuances of underwriting and can guide you toward carriers that are more likely to approve your application.
How to Request Quotes for High-Risk Situations
Requesting quotes for high-risk situations requires a strategic approach. First, gather all relevant medical records, including doctor's notes, lab results, and prescription history. Having this information ready will streamline the process and show insurers that you are organized and transparent. Next, identify the specific reason for your denial and research which carriers are known to be lenient with that condition. An independent agent can help with this research.
When requesting quotes, be upfront about your denial history. Agents need to know what happened so they can avoid submitting your application to carriers that will likely decline you again. They can also advise you on which policy types (term, whole, final expense) are most realistic for your situation. For high-risk cases, final expense or guaranteed issue policies are often the most accessible options.
Finally, do not give up if the first few quotes are unfavorable. The insurance market is diverse, and there may be a carrier willing to insure you at a higher premium. Keep an open mind and consider working with a specialist who focuses on impaired risk. With persistence and the right guidance, you can find coverage that provides financial security for your loved ones. To get started, you can reach out to our team at (833)-212-4240 for expert assistance and to explore your options.
Remember that a denial is not a reflection of your worth or your insurability. It is simply a mismatch between your current profile and a particular carrier's guidelines. By taking the steps outlined above, you can overcome this obstacle and secure the protection your family deserves.