Best Whole Life Insurance: How to Choose in 2026
Find the best whole life insurance with our comparison guide. Call (833)-212-4240 for expert help securing lasting coverage.
By Tavira Solen
Whole life insurance is one of the few financial products that can provide lifelong protection, build cash value, and lock in your premiums forever. But with dozens of carriers offering different dividends, riders, and policy structures, finding the best whole life insurance policy can feel overwhelming. This guide cuts through the marketing noise and shows you how to identify the strongest whole life policies for your situation, whether you are a parent protecting young children, a business owner planning for succession, or a retiree looking to leave a legacy.
What Makes Whole Life Insurance the Best Choice for Certain Goals
Whole life insurance is a type of permanent life insurance that stays in force for your entire lifetime as long as premiums are paid. Unlike term insurance, which expires after a set number of years, whole life builds guaranteed cash value and offers fixed premiums that never increase. That predictability is why many families use whole life as the foundation of a long-term financial plan. The best whole life insurance policies combine three features: guaranteed death benefit, guaranteed cash value growth, and optional dividends from mutual insurers.
However, whole life is not the right fit for everyone. If your primary need is temporary income replacement while children are young, a term policy may be more cost-effective. But if you want coverage that lasts forever, a savings component you can borrow against, and estate planning benefits, whole life shines. The key is to compare policies from highly rated mutual companies and evaluate them on cost, cash value projections, and dividend history. You can start by requesting personalized whole life quotes through a comparison platform to see side-by-side illustrations from multiple carriers.
When evaluating the best whole life insurance for your family, consider these core components:
- Guaranteed cash value: The minimum amount your policy will accumulate, regardless of dividend performance.
- Dividend eligibility: Mutual insurers may pay dividends, which can buy additional coverage or reduce premiums.
- Loan and withdrawal options: Access to cash value via policy loans, though unpaid loans reduce the death benefit.
- Rider availability: Options like waiver of premium, accidental death benefit, or child term riders.
- Carrier financial strength: Ratings from A.M. Best, Moody's, and S&P indicate a company's ability to pay claims.
After reviewing these components, you will have a solid basis for comparing whole life illustrations. Remember that dividends are not guaranteed, so focus on the guaranteed column first. A policy with strong guarantees and a long history of consistent dividend payments is often a better choice than one with flashy projected values but weak fundamentals.
How to Compare Whole Life Insurance Policies Step by Step
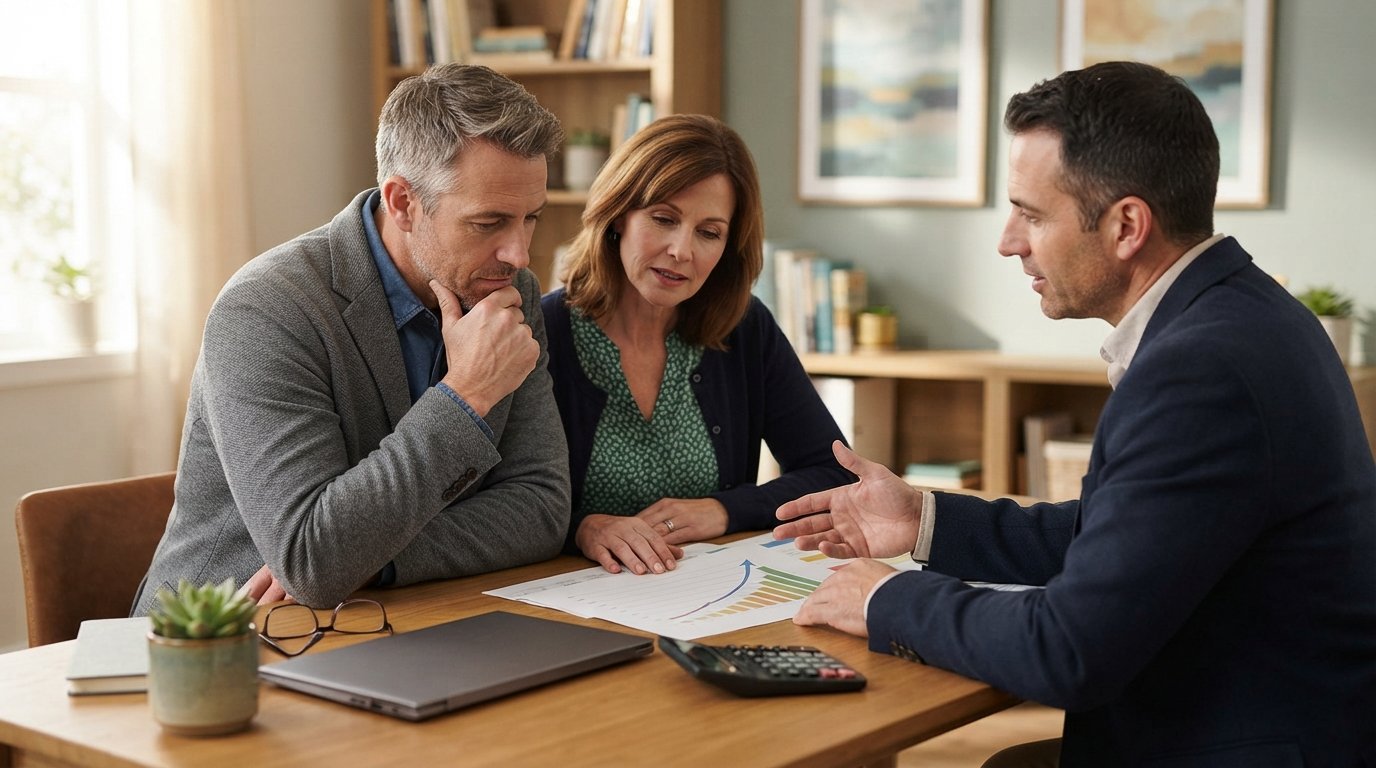
Comparing whole life insurance is more complex than comparing term policies because you must evaluate both the insurance protection and the savings element. Start by determining how much death benefit you need, then request illustrations from at least three highly rated carriers. Use the same inputs (age, health class, coverage amount) so you can make an apples-to-apples comparison. The best whole life insurance policy for you will balance affordability with strong guaranteed cash value growth.
Follow this sequence to streamline your comparison:
- Assess your coverage need: Calculate income replacement, debts, education costs, and final expenses.
- Check carrier ratings: Focus on insurers with A+ or better financial strength ratings.
- Review guaranteed illustrations: Compare the guaranteed cash value and death benefit at years 10, 20, and 30.
- Evaluate dividend history: Look at the insurer's dividend scale over the past decade, not just the current year.
- Consider riders and flexibility: Determine if you need disability waiver, accelerated death benefit, or policy loan features.
Once you have gathered illustrations, do not just pick the lowest premium. A slightly higher premium from a mutual company with a strong dividend history can outperform a cheaper policy from a stock insurer over 20 or 30 years. Also, ask about policy fees and surrender charges, which can erode cash value in the early years. For a deeper dive into how whole life builds wealth, see our guide on whole life insurance plans that build lasting family wealth.
After narrowing your options, share the illustrations with a licensed agent who can explain the fine print. Many buyers overlook the impact of policy loans or the difference between direct recognition and non-direct recognition dividends. A good agent will help you understand these nuances without pressure. You can also use online tools to get a quick side-by-side view of quotes from multiple carriers, which saves time and reduces the chance of missing a better offer.
Top Features to Look for in the Best Whole Life Insurance
The best whole life insurance policies share several traits that make them stand out in a crowded market. First, they are issued by mutual insurers with a long track record of paying dividends, because dividends can significantly boost cash value over time. Second, they offer strong guaranteed cash value growth, meaning the policy is not overly dependent on non-guaranteed projections. Third, they provide flexible access to cash value through loans or withdrawals, which can be useful for emergencies, education, or retirement income.
Beyond the core policy, consider these additional features that can make a whole life policy more valuable:
- Paid-up additions rider: Allows you to add extra coverage and accelerate cash value growth with additional premiums.
- Waiver of premium rider: Keeps the policy in force if you become disabled and cannot pay premiums.
- Accelerated death benefit rider: Lets you access a portion of the death benefit if diagnosed with a terminal illness.
- Child term rider: Provides inexpensive coverage for children, often convertible to permanent later.
- Guaranteed insurability rider: Allows you to buy more coverage at set intervals without a new medical exam.
These features can add cost, so prioritize based on your needs. A young family might value the child rider and waiver of premium, while a business owner might focus on the paid-up additions rider for cash accumulation. Always ask for a customized illustration that includes the riders you are considering, so you can see the impact on both premium and cash value. The best whole life insurance policy is one that aligns with your long-term goals and remains affordable for decades.
Another often-overlooked factor is the insurer's customer service and claims-paying reputation. You can check J.D. Power ratings and NAIC complaint ratios to gauge how well a company treats its policyholders. A policy is only as good as the company behind it, so do not sacrifice service quality for a slightly lower premium.
Common Mistakes to Avoid When Buying Whole Life Insurance
Many buyers regret their whole life purchase because they were sold a policy that did not fit their needs or budget. One common mistake is buying too much coverage relative to income, leading to lapsed policies and lost cash value. Another is failing to understand that cash value takes years to build, so whole life is not a short-term savings vehicle. A third mistake is ignoring the difference between guaranteed and projected values, which can lead to unrealistic expectations.
Here are the most frequent pitfalls to watch for:
- Overpaying for coverage: Whole life premiums are higher than term, so ensure the policy fits your budget for the long haul.
- Not comparing multiple carriers: The same coverage can vary significantly in price and cash value projections.
- Surrendering early: Surrender charges can be steep in the first 10 to 15 years, often exceeding the cash value.
- Taking large policy loans: Unpaid loans accrue interest and reduce the death benefit, potentially causing the policy to lapse.
- Misunderstanding dividends: Dividends are not guaranteed and can decrease, so do not rely on them for essential expenses.
Avoiding these mistakes starts with education. Work with an agent who explains the policy in plain language and provides a full illustration. Do not be afraid to ask questions about fees, surrender charges, and loan interest. A transparent agent will welcome the scrutiny. If you feel pressured to sign without understanding the details, walk away. The best whole life insurance policy is one you fully understand and can comfortably afford.
Finally, review your policy periodically, especially after major life events like marriage, a new child, or a home purchase. You may need to adjust coverage or riders. Whole life policies are flexible in some ways but rigid in others, so regular reviews ensure your coverage keeps pace with your life.
How Whole Life Fits into a Broader Financial and Estate Plan
Whole life insurance is not just a death benefit; it is a financial tool that can support estate planning, business succession, and tax diversification. For high-net-worth families, whole life can provide liquidity to pay estate taxes without forcing the sale of illiquid assets like real estate or a family business. For business owners, a whole life policy can fund a buy-sell agreement or provide key person protection. For retirees, the cash value can supplement retirement income through policy loans, though this strategy requires careful management to avoid lapsing the policy.
When integrating whole life into your estate plan, consider how the death benefit will be received. Life insurance proceeds are generally income-tax-free to beneficiaries, but they may be subject to estate taxes if you own the policy. An irrevocable life insurance trust (ILIT) can remove the proceeds from your taxable estate, but it also gives up control. Consult with an estate attorney to determine if an ILIT is appropriate for your situation.
For business owners, whole life can be used in several advanced strategies:
- Buy-sell funding: Provides cash for surviving partners to buy out a deceased owner's share.
- Key person insurance: Protects the business against the loss of a critical employee.
- Executive bonus plans: Offers a tax-deductible benefit to key employees while building cash value.
- Split-dollar arrangements: Shares premium costs and death benefit between the business and the insured.
These strategies require careful legal and tax planning, so work with professionals who understand both insurance and business law. The best whole life insurance policy in a business context is one that is properly structured to meet the specific goals of the owners and the business.
Beyond estate and business planning, whole life can serve as a conservative asset in your portfolio. The cash value grows tax-deferred, and policy loans are generally not taxable as long as the policy remains in force. This can provide a source of liquidity that is not correlated with stock market swings. However, whole life is not a replacement for a diversified investment portfolio; it is a complement. Treat it as a fixed-income-like asset with insurance benefits.
Before committing to a whole life policy, ask yourself if you have adequate term coverage, an emergency fund, and retirement savings in place. Whole life works best for those who have maxed out other tax-advantaged options and have a permanent need for insurance. If you are unsure, a fee-only financial planner can help you evaluate whether whole life is appropriate for your overall financial plan.
Where to Get the Best Whole Life Insurance Quotes
Finding the best whole life insurance requires access to multiple carriers and the expertise to compare complex illustrations. That is where a dedicated quote-comparison platform can help. Instead of contacting dozens of insurers individually, you can request personalized whole life quotes from a network of licensed agents who represent top-rated carriers. This saves time and gives you a clearer picture of the market.
When you use a comparison service, be prepared to provide basic information such as your age, health status, and coverage amount. You will then receive quotes from participating insurers, which you can review side by side. Pay attention to the guaranteed cash value and death benefit, not just the premium. A licensed agent can walk you through the differences and help you choose the policy that best fits your needs. For a reliable starting point, consider USLifeQuote, which connects you with licensed agents who can analyze your needs and suggest affordable life insurance plans.
Remember that quotes are not guarantees of coverage. Underwriting and final rates depend on your health and other factors. But comparing quotes early gives you a realistic sense of what you can expect to pay. It also helps you identify which carriers are most competitive for your age and health profile. The best whole life insurance policy is the one that offers the strongest guarantees and features at a price you can sustain for life.
Do not rush the process. Whole life is a long-term commitment, and the wrong policy can cost you thousands in lost cash value and unnecessary premiums. Take the time to compare at least three illustrations, ask questions, and consult with a financial professional if needed. With careful research and the right guidance, you can secure a policy that protects your family and builds wealth for decades.
Whole life insurance can be a powerful tool for financial security when chosen wisely. By focusing on guaranteed values, carrier strength, and features that match your goals, you can find the best whole life insurance policy for your family. Start your comparison today and take the first step toward lasting protection.