Best Time to Buy Life Insurance for a New Baby
The best time to buy life insurance for a new baby is now. Call (833)-212-4240 to lock in low rates and protect your family's future.
By Orin Valtor
The moment a baby enters your life, every decision feels heavier. You are suddenly responsible for a human being who depends on you for everything, and the future you once imagined for yourself now includes daycare costs, college funds, and the quiet hope that you will be around to see it all happen. In the middle of sleepless nights and endless pediatrician visits, life insurance might feel like just one more item on a list that never ends. But here is the truth that many new parents learn too late: the best time to buy life insurance for a new baby is not months down the road when things settle down. It is now, while your health is fresh, your age is low, and your child is still small enough to fit in the crook of your arm.
This article walks you through the timing question from every angle: the cost of waiting, how to prioritize coverage in that chaotic first year, the difference between a child rider and a separate juvenile policy, and how parental leave changes what you can realistically afford. By the end, you will have a clear, practical roadmap from birth to your first policy anniversary.
Why Waiting for a Lower Rate Rarely Works in Your Favor
There is a common misconception among new parents that life insurance rates will somehow improve if they wait. Perhaps you think you will lose the baby weight, get your blood pressure under control, or finally kick the habit. Maybe you assume that once you are past the newborn fog, you will have more time to shop around and find a better deal. The reality is that life insurance pricing moves in one direction as you age: up. Every birthday adds a little more to your premium, and every new health diagnosis, however minor, can push you into a higher risk category.
Insurance companies price policies based on risk, and age is one of the biggest factors in that calculation. A healthy 30-year-old will almost always pay less for the same coverage than a healthy 35-year-old. If you are a new parent in your twenties or early thirties, you are sitting on a window of opportunity that will not stay open forever. Waiting even a year or two can mean paying more each month for decades, or worse, facing a health issue that makes coverage unaffordable or unavailable.
Consider this: a 30-year-old woman in good health might pay around $25 per month for a $500,000, 20-year term policy. The same woman at 35 could pay $35 or more for identical coverage. Multiply that difference over 20 years, and you are looking at thousands of dollars lost simply because you waited. That money could have gone into a college fund, a emergency savings account, or a family vacation. The cost of waiting is not just financial, either. It is the peace of mind you give up every day you go without coverage.
For new parents, the calculus is even starker. You are not just insuring yourself; you are insuring the financial stability of your child. If something happened to you, would your family be able to cover the mortgage, childcare, and future education costs? Life insurance is the tool that answers that question with a resounding yes. And the best time to buy life insurance for a new baby is when that baby is still a newborn, not when they are blowing out candles on a first birthday cake.
Coverage Priorities in the First Year: Income Replacement Before College Savings
New parents are bombarded with advice about saving for college. It starts before the baby is even born, with 529 plans and custodial accounts and grandparent contributions. While saving for education is important, it should not come before protecting your family's income. If you die or become disabled, your child's college fund will not matter if there is no money to keep the lights on, pay the rent, or put food on the table. Income replacement is the foundation of any sound financial plan for a growing family.
Think about what your income covers right now. It pays for housing, groceries, utilities, childcare, transportation, and healthcare. It also funds the savings that will eventually go toward college. If that income disappeared tomorrow, your family would face an immediate crisis. Life insurance replaces that income so your partner can grieve without also worrying about how to pay the bills. Only after you have secured income replacement should you turn your attention to longer-term goals like education savings.
Here is a simple framework for prioritizing coverage in the first year:
- First, replace your income. Aim for coverage that is 10 to 15 times your annual income. This ensures your family can maintain their standard of living for years, not just months.
- Second, cover outstanding debts. Include your mortgage, car loans, student loans, and any credit card balances in your coverage calculation.
- Third, account for future expenses. Childcare, healthcare, and education costs should be factored into the total, but they come after the basics.
- Fourth, consider final expenses. Funeral costs and medical bills at the end of life can be significant, so make sure your policy includes enough to cover them.
- Finally, revisit college savings. Once your income replacement and debt coverage are in place, you can confidently direct extra funds toward a 529 plan or other education savings vehicle.
This order of operations matters because it protects your family from the most immediate and devastating risks first. A college fund is a wonderful gift, but it will not help your child if they are forced to move in with relatives because the mortgage went unpaid. By prioritizing income replacement, you build a safety net that makes every other financial goal possible.
Adding a Child Rider Versus a Separate Juvenile Policy
Once you have secured your own coverage, you may want to consider insuring your child as well. There are two main ways to do this: adding a child rider to your existing policy or purchasing a separate juvenile policy. Each option has distinct advantages and trade-offs, and the right choice depends on your goals and budget.
A child rider is an add-on to your life insurance policy that provides a small amount of coverage for your children, typically between $5,000 and $25,000. It is usually inexpensive, often just a few dollars a month, and it can cover all current and future children under a single rider. The main benefit is simplicity and cost. You do not need a separate application or medical exam for your child, and the coverage can be converted to a permanent policy later without evidence of insurability. However, the coverage amount is relatively small, and it is designed more for final expenses than for long-term financial protection.
A separate juvenile policy, on the other hand, is a standalone life insurance policy for your child. It can be term or permanent, and the coverage amount can be much larger than what a child rider offers. The biggest advantage of a juvenile policy is that it locks in your child's insurability at a young age. If your child develops a health condition later in life, they will still have coverage in place. Some permanent juvenile policies also build cash value that can be used for future needs like education or a down payment. The downside is cost and complexity. A separate policy requires its own application, possibly a medical exam, and a higher premium than a rider.
For most families, a child rider is a sensible starting point. It provides affordable coverage for the unthinkable while keeping things simple. As your child grows and your financial situation evolves, you can reassess whether a separate juvenile policy makes sense. The key is to have some form of coverage in place from the beginning, rather than waiting until you have everything figured out.
How Parental Leave and Reduced Income Affect the Quote You Can Afford
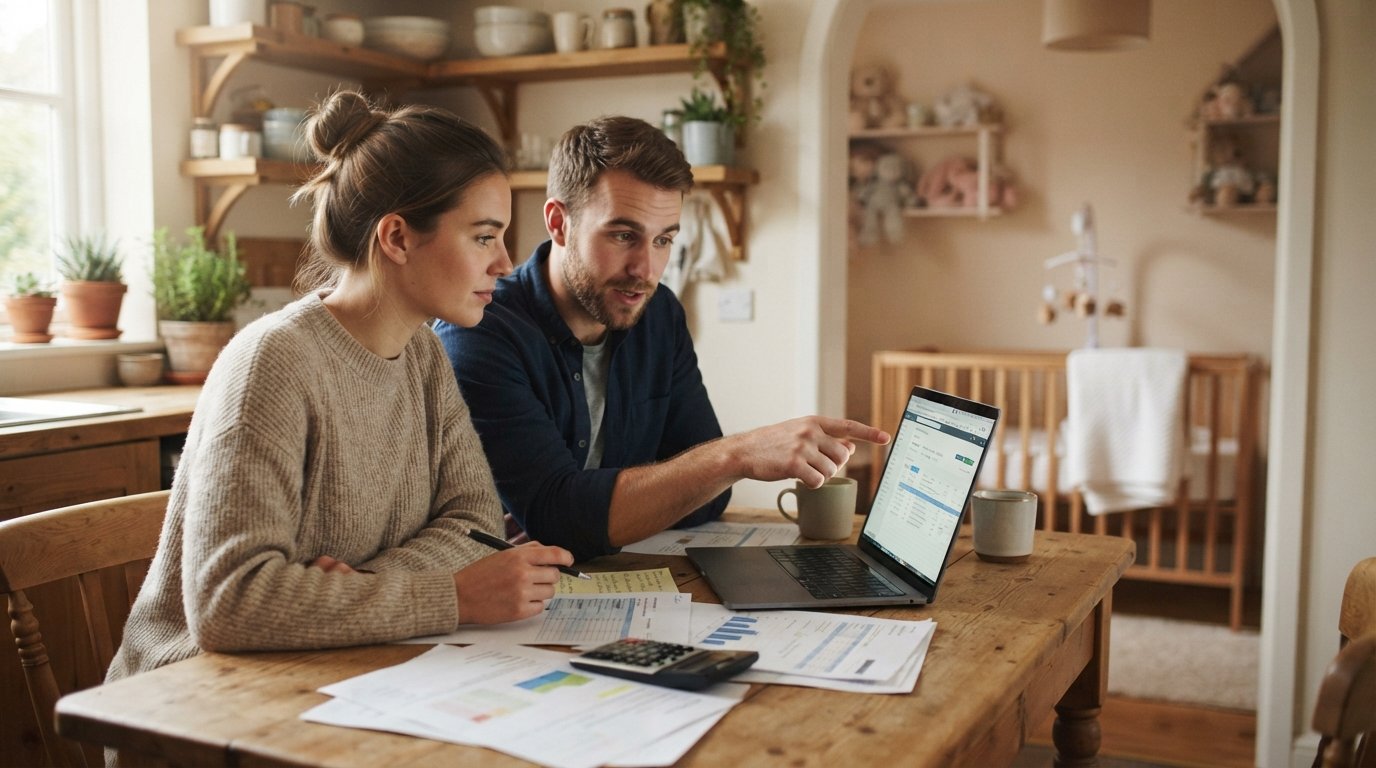
Parental leave is a wonderful time to bond with your new baby, but it often comes with a significant drop in income. Whether you are taking unpaid leave, partial pay, or a short-term disability benefit, your household budget looks different during those weeks and months. This temporary reduction in income can make the idea of adding a new expense like life insurance feel daunting. However, it is important to separate short-term cash flow from long-term financial planning.
Life insurance premiums are based on your age, health, and coverage amount, not on your current employment status. You can apply for coverage while on parental leave, and your premium will not be higher simply because you are not receiving a full paycheck. In fact, applying during leave can be advantageous. You may have more time to research options, speak with agents, and complete the application process without the distractions of a full work schedule. The key is to choose a coverage amount that fits your current budget while still providing adequate protection.
If money is tight during leave, consider starting with a smaller term policy and increasing coverage later. A 10-year term policy with a modest death benefit can be surprisingly affordable, often less than the cost of a streaming subscription. You can also look for policies with flexible premium options or simplified issue policies that do not require a medical exam. The goal is to get some coverage in place now, then adjust as your income stabilizes. Remember, the best time to buy life insurance for a new baby is not when you have the most money; it is when you have the most need, and that need is immediate.
It is also worth noting that many employers offer group life insurance as part of their benefits package. If you are on leave, check whether your coverage continues and whether you can supplement it with an individual policy. Group coverage is often limited and may not be portable if you change jobs, so an individual policy is a more reliable long-term solution. For a deeper look at how permanent coverage builds value over time, see our guide on whole life insurance cash value growth.
A Simple Checklist from Birth to First Policy Anniversary
Bringing a new baby home is a whirlwind, and it is easy to let important tasks slip through the cracks. To make the process manageable, break it down into small, actionable steps. Here is a checklist that takes you from the hospital discharge to your first policy anniversary, ensuring you never lose sight of your family's protection.
- Within the first two weeks: Gather your financial documents, including income statements, debt balances, and existing coverage. Use a simple calculator to estimate how much life insurance you need. Aim for 10 to 15 times your income, plus enough to cover debts and future expenses.
- Within the first month: Request quotes from multiple providers. You can use an online comparison tool or work with an independent agent who can shop around on your behalf. Compare term lengths, coverage amounts, and premiums. Do not forget to factor in your parental leave budget.
- Within the first two months: Complete the application for your chosen policy. If a medical exam is required, schedule it promptly. Be honest about your health history and lifestyle habits; accuracy prevents delays and surprises later.
- Within the first six months: Once your policy is approved and in force, review your beneficiary designations. Make sure your partner, trust, or guardian is listed correctly. Store a copy of your policy in a safe place and share the details with your partner.
- By the first policy anniversary: Reassess your coverage. Has your income changed? Have you had another child? Have you taken on new debt? Adjust your coverage accordingly. Also, check whether your child rider or juvenile policy needs updating. This annual review keeps your protection aligned with your life.
Following this checklist turns a daunting task into a series of manageable steps. It also ensures that you are not scrambling to find coverage during a crisis. The first year of your baby's life is a time of enormous change, and having a clear plan for life insurance gives you one less thing to worry about.
Turning Intent into Action with the Right Partner
Understanding the best time to buy life insurance for a new baby is only half the battle. The other half is taking action. Many parents know they need coverage but feel overwhelmed by the options, the jargon, and the fear of making the wrong choice. That is where a trusted partner can make all the difference. At LifeAgency, licensed agents analyze your specific needs and suggest affordable plans from a range of carriers, so you can compare quotes side by side without pressure.
Whether you are looking for a simple term policy to cover your income or a permanent policy with cash value, the right agent can help you navigate the process from start to finish. They can explain the difference between riders and standalone policies, help you estimate how much coverage you need, and find options that fit your budget, even during parental leave. The goal is to get you covered quickly and confidently, so you can focus on what matters most: your new baby.
Do not let another month go by without protecting your family's financial future. The best time to buy life insurance for a new baby is right now, while your health is good, your rates are low, and your child is still small. With a clear checklist, a realistic budget, and the right support, you can check this critical task off your list and enjoy the peace of mind that comes with knowing your family is covered.